The appeal of hard money loans is that they're supposed to close faster than bank loans. Hard money lenders approve loans based on a deal's profitability, with the property itself as collateral, rather than underwriting your entire financial profile (e.g., income, employment history, debt-to-income ratio, tax returns).
But from what we see, many hard money lenders don't deliver on this promise. Many advertise fast, one- to two-week closings, but take 30 days or more.
That's because even though hard money underwriting is simpler, most lenders still run loans through slow, outdated workflows much like a bank's. Your file can sit in a queue for days before anyone reviews it, then get passed between departments, with each approval needing sign-off from several people.
So, we put this guide together to help you gauge a lender's true closing speed instead of taking their word for it. Then, we compare popular hard money lenders in Connecticut.
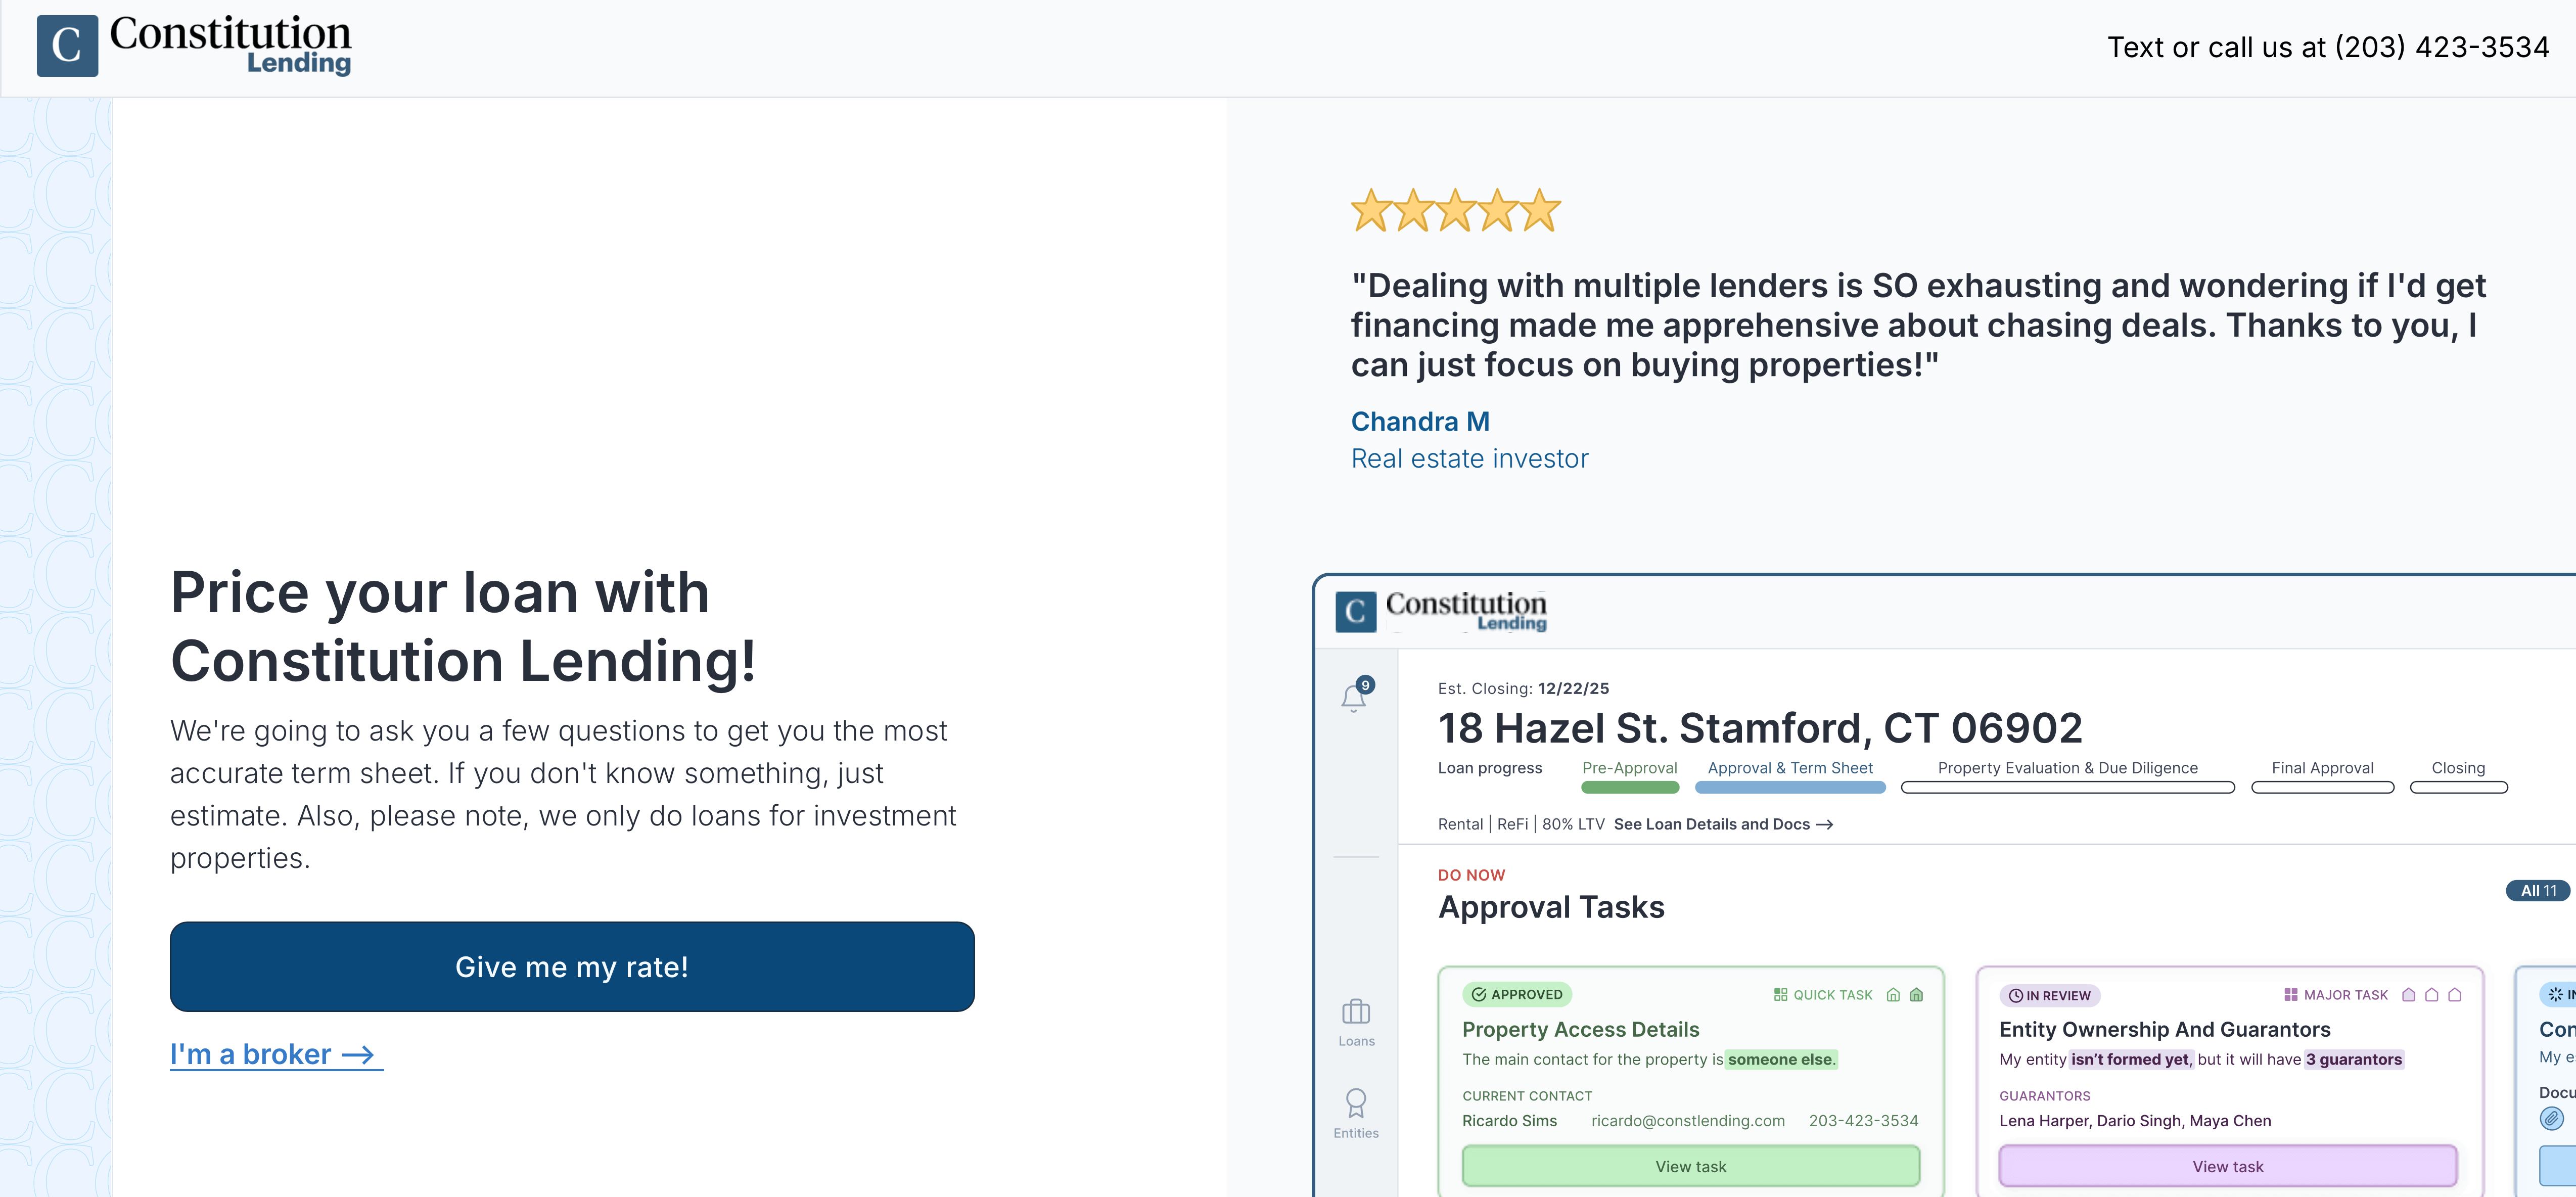
Note: We're Constitution Lending, a direct hard money lender based in Greenwich, Connecticut. We've funded hundreds of millions of dollars in hard money loans across the state, closing most within 7 to 14 days. You can enter your deal into our loan pricer to see your rate, leverage, and term sheet.
Factors to Consider When Choosing a Connecticut Hard Money Lender
1. How quickly can they issue loan quotes, term sheets, and pre-approval letters?
Rather than taking a lender's word on closing speed, look at how long it takes them to issue quotes, term sheets, and pre-approval letters, since that is a good proxy for their overall closing speed.
These documents take almost no work to produce, so if a lender needs days to send them, expect the same slow processes to delay underwriting, the appraisal, and closing.
The fastest hard money lenders use automated pricing tools that return all three documents within minutes of entering your deal. This shows they value closing speed and likely use more automated tools and systems to speed up the process as you near closing.
2. Are they actually based in Connecticut?
Many lenders licensed in Connecticut are headquartered elsewhere and treat it as one of dozens of markets.
This matters more than most borrowers expect. An out-of-state lender underwrites your deal without first-hand knowledge of your local market, and that can hurt you in a few ways:
- Lower valuations. Without knowing local sales, they may set a conservative ARV, which shrinks your loan or raises your rate.
- Slower third-party work. They often lack relationships with Connecticut appraisers and title companies, so those steps take longer.
- Late compliance issues. Unfamiliarity with Connecticut's transfer taxes and closing requirements can surface problems right before funding.
We recommend working with a Connecticut-based lender instead. Local knowledge speeds up appraisals and title work, reduces the likelihood of surprises at closing, and leads to more accurate valuations.
3. Do they have real estate investing experience?
Many hard money lenders employ loan officers and underwriters with little or no experience flipping or renovating properties. They underwrite deals using a lending algorithm, and if a deal falls outside those parameters, it might get rejected, even when the numbers make sense to an investor.
We recommend working with lenders who have bought and renovated properties themselves, since they're more likely to understand your plan and fund deals that fall outside traditional lending requirements.
4. Are they a direct lender or a broker?
Many companies that market themselves as hard money or private money lenders are actually brokers. They don't fund loans; they connect you with a lender.
This creates a problem: they may review your file and think you qualify, but if the funding lender sees a problem the broker missed, your loan can fall through days before closing, with your earnest money on the line.
We advise partnering with direct lenders for your hard money loans. A direct lender uses its own capital and makes its own decisions in-house. They don't have to wait for another lender to complete underwriting before giving you a yes or no, reducing the likelihood of last-minute rejections and drama.
5. What are their qualification requirements?
Hard money lenders set different limits on how much they'll lend, which property types they accept, and who they'll lend to, so check these before you apply:
- Loan-to-cost (LTC). This is the share of your purchase price and renovation budget the lender will cover. Many cap it around 85% to 90%, so you pay the rest in cash as your down payment.
- After-repair value (ARV) limit. Most lenders also cap the loan at roughly 70% to 75% of the property's expected value after renovation, which can bring your loan below the LTC limit.
- Rehab funding. Some lenders finance 100% of your renovation costs, while others only cover part of them.
- Credit and experience. Minimum credit scores often start around 650 to 680, and some lenders offer lower leverage or higher interest rates to first-time flippers.
- Loan size. Minimum loan amounts vary, which matters if you're buying lower-priced properties.
Top Connecticut Hard Money Lenders Compared
1. Constitution Lending: A Greenwich-Based Hard Money Lender That Closes in 7 to 14 Days
Constitution Lending is a direct hard money lender headquartered in Greenwich, Connecticut. Before we started lending, we flipped and renovated investment properties across the state, and slow, unreliable lenders regularly cost us deals.
Lenders would promise to close in a week, then take a month or more while cash buyers moved ahead of us. So, we started Constitution Lending to help Connecticut investors close quickly and beat cash buyers to undervalued real estate.
Here's what borrowers say about working with us:

How We Close Most Loans in 7 to 14 Days
We use automated tools to speed up every step in the process from application to closing. Here's how the process works.
Enter a few details about your deal into our pricer, and it instantly returns three loan options. Choose one, and your quote, term sheet, and pre-approval letter are available immediately.
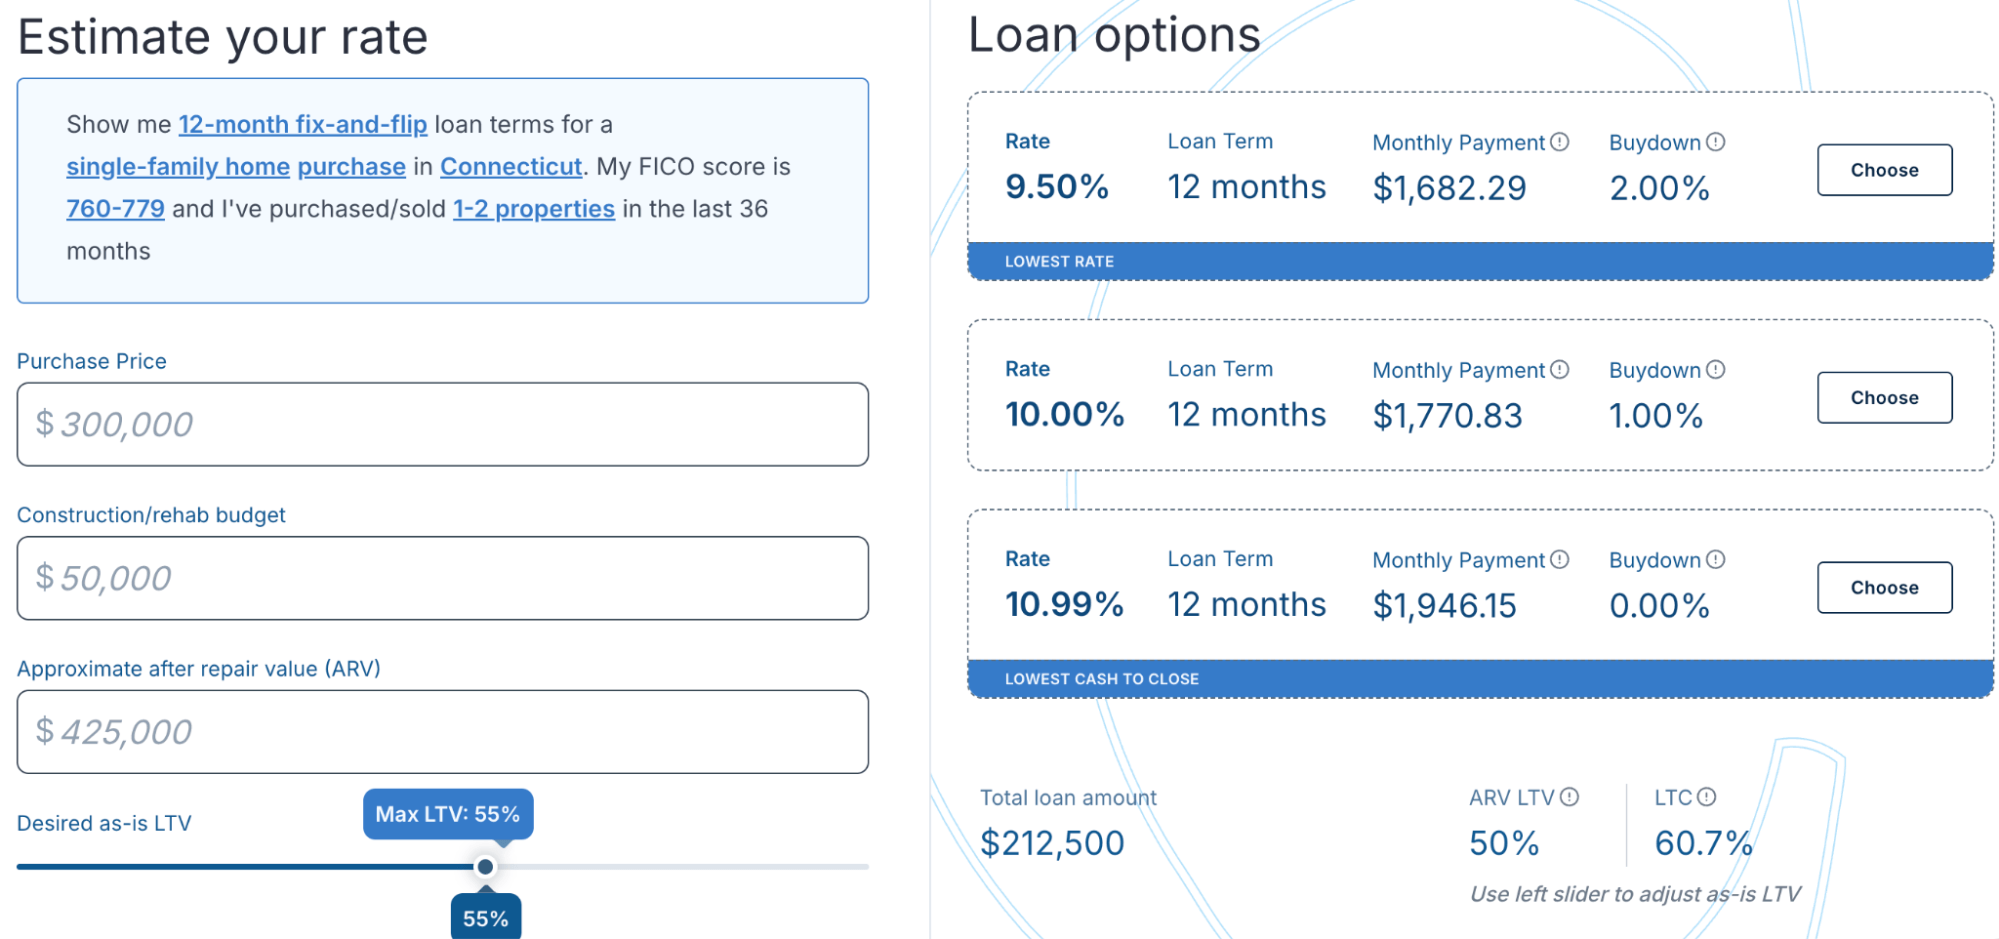
You'll get access to our documents portal at the same time. It lists every document your loan requires, from entity documents to your scope of work, so you can submit everything at once instead of answering requests one by one.

With a complete file from the start, we can move through underwriting and close in 7 to 14 days. When a borrower's deal has been at risk, we've closed in as little as four days.
We're Based in Greenwich and Know Connecticut's Market
Constitution Lending is headquartered in Greenwich, and before we started lending, we bought and renovated properties across the state ourselves.
That experience taught us what renovated homes sell for in towns like Stamford, Norwalk, Hartford, and New Haven. It also gave us firsthand knowledge of the state’s transfer taxes, title norms, and disclosure rules. We've built relationships with local appraisers and title companies we can count on to move quickly.
For you as a borrower, that means:
- Better terms. We set ARVs the way a local investor would, which often means more leverage, a lower rate, and fewer extra conditions.
- Faster appraisals and title work. Our local appraisers and title partners keep those steps on schedule.
- Fewer closing surprises. We've handled Connecticut-specific issues on hundreds of deals, so we can resolve them quickly if they come up.
Your Deal Is Reviewed by Investors, Not Just an Algorithm
Our team has flipped and renovated properties across Connecticut, so the people reviewing your loan know what it's like to be in your position. Your deal isn't being evaluated by software or a loan officer with no investing experience.
Instead, we look at your deal from your point of view: the purchase price, the renovation plan, and what the property will sell for once the work is done. That lets us make exceptions and fund deals other lenders often turn down.
Read more: Hard Money Loan Requirements: 4 Key Factors Lenders Consider
We Fund Your Loan Ourselves
Constitution Lending is a direct lender, so we fund your loan and make the final decision. After evaluating thousands of loan applications, we can usually tell whether you qualify shortly after you submit your documents.
Unlike loan brokers, we don't send your file to another lender and wait for its underwriters to finish. That removes the possibility of late rejections that happen when lenders find problems brokers missed.
Our Loan Programs and Requirements
We lend $150,000 to $3 million across four programs, with no personal income verification on any of them:
Get a Fast, Reliable Connecticut Hard Money Loan with Constitution Lending
Run your deal through our automated pricer to get an instant quote, term sheet, and pre-approval letter.
We’re proud of the lending process we’ve built, and we believe it makes us the best option for Connecticut investors who need to compete with cash buyers. But if you’d like to compare other options, here are nine more lenders worth considering.
2. RCN Capital

RCN Capital has lent to real estate investors since 2010 from its headquarters in South Windsor, Connecticut, and has originated more than $8.2 billion across over 37,000 loans.
Speed: RCN typically issues term sheets the next business day and makes pre-approval decisions within 24 hours of a complete submission. It advertises closings in as few as 10 business days.
Connecticut presence: RCN is headquartered in Connecticut and also lends nationwide.
Real estate experience: RCN sets leverage by experience tier and reserves its highest leverage for investors with 10 or more completed flips and a 720+ credit score.
Direct lender: RCN funds its own loans, but as a self-described wholesale lender, much of its volume comes through mortgage brokers. Going to RCN directly keeps a middleman out of your deal.
Requirements: Up to 100% of the purchase price and renovation costs for top-tier borrowers, capped at 75% of ARV, with 12- to 18-month terms and a minimum credit score of around 650.
3. Sachem Capital
Sachem Capital is a publicly traded real estate finance company headquartered in Branford, Connecticut, that has been in hard money lending since 2010. It focuses on larger bridge, renovation, and construction loans for residential and commercial real estate investors along the East Coast.
Speed: Investors submit their project details, and Sachem's in-house team reviews the request before issuing a term sheet. Most of its loans close in 30 to 45 days, though some close faster when every requirement is met.
Connecticut presence: Sachem is based in Connecticut and lends in 14 states, along with select New York counties.
Real estate experience: Sachem's underwriting weighs the property, the borrower's experience, and the project itself rather than relying mainly on credit scores or income.
Direct lender: Sachem originates, services, and manages its own loan portfolio, so lending decisions stay in-house.
Requirements: Its short-term loans range from $500,000 to $25 million with 12- to 36-month terms, and most carry no prepayment penalty. The $500,000 minimum puts many single-family flips below its range.
4. BridgeWell Capital

BridgeWell Capital has financed real estate investors since 2008 and reports providing more than $500 million to investors. It lends in Connecticut alongside several other states, including Illinois, Massachusetts, and Virginia.
Speed: BridgeWell says its fix-and-flip loans close in as few as 10 business days.
Connecticut presence: BridgeWell runs Connecticut-specific loan programs and says its team knows the greater Connecticut market, though it serves investors in multiple states.
Real estate experience: BridgeWell says its management team has more than 30 years of real estate investment experience, and it approves deals based on whether the investment makes sense and offers a solid margin.
Direct lender: BridgeWell lends from in-house capital, so funding doesn't depend on an outside lender.
Requirements: Fix-and-flip loans from $100,000 to $2 million, up to 75% LTV, 100% of rehab costs funded, an origination fee of 1.5% to 3%, a $75,000 minimum purchase price, and a 620 minimum credit score.
5. Stratton Equities

Founded in 2017 by CEO Michael Mikhail, Stratton Equities is a direct hard money and non-QM lender headquartered in Pine Brook, New Jersey. Its product menu is one of the widest on this list, from fix-and-flip, bridge, and rental loans to no-doc and foreclosure bailout financing.
Speed: Stratton's own program page says its fix-and-flip loans close in an average of 21 to 25 days.
Connecticut presence: Stratton lends nationwide, including Connecticut, from its New Jersey headquarters.
Real estate experience: Stratton says its company is owned and operated by experienced real estate investors.
Direct lender: Stratton funds loans directly rather than placing them with another lender.
Requirements: Up to 90% of the purchase price and 100% of rehab costs for experienced investors, capped at 75% of ARV, with loans from $100,000 to $5 million on single-family, multifamily, condo, and mixed-use properties and 9- to 24-month terms.
6. Unitas Funding
Unitas Funding is a nationwide direct lender of private money loans backed by institutional capital, with fix-and-flip, construction, and bridge programs, plus DSCR loans for investors building a rental portfolio.
Speed: Unitas says it can often issue pre-approvals and term sheets the same day and close in as few as 10 business days once documentation is complete.
Connecticut presence: Unitas has a dedicated Connecticut lending program but serves investors across the country.
Real estate experience: Unitas says it evaluates ARV using comparable sales and market analysis rather than rigid formulas.
Direct lender: Unitas lends directly in most states, though in some, such as Utah, it accepts applications only through licensed brokers.
Requirements: Fix-and-flip loans up to 92.5% LTC and 75% ARV, with 12- to 24-month terms and loan amounts up to $2.5 million.
7. West Forest Capital
Headquartered in New York City, West Forest Capital is an asset-based lender offering fix-and-flip and commercial loans to investors in Connecticut, New York, New Jersey, and several other East Coast states. Its site highlights funded Connecticut deals, including a fix-and-flip in New Britain.
Speed: West Forest offers same-day pre-approvals and says it funds loans in 3 to 12 days.
Connecticut presence: West Forest has dedicated pages for Hartford, New Haven, and Milford, though its headquarters is in New York.
Real estate experience: West Forest structures loans around the value of the asset and says it has occasionally financed more than 100% of the purchase and rehab.
Direct lender: West Forest is a direct lender that also works with mortgage brokers.
Requirements: Loans up to $5 million covering up to 85% of the purchase price and 100% of renovation costs, with the total loan held to roughly 65% to 70% of ARV and terms up to 36 months.
8. Asset Based Lending (ABL)
Asset Based Lending is a direct balance-sheet lender headquartered in Jersey City, New Jersey, that lends in more than 40 states. It's best known for its zero-point program, which waives origination points on qualifying loans.
Speed: ABL pre-qualifies most borrowers within 24 hours and says loans can close in as few as 20 days, depending on documentation, the appraisal, and title.
Connecticut presence: ABL says its team has lent in Connecticut and the Northeast for more than a decade, and it lists funded deals in towns like Bridgeport, Hartford, and Fairfield.
Real estate experience: ABL underwrites based on the property and the investor's exit strategy, such as a sale or refinance, rather than income or credit history.
Direct lender: ABL lends from its own balance sheet, so borrowers work directly with the decision-makers.
Requirements: Fix-and-flip loans from $75,000 to $50 million with up to 92.5% LTC, up to 90% of the purchase price, 100% of rehab, and 12- to 24-month terms.
9. Easy Street Capital

Easy Street Capital is an Austin-based private lender, founded in 2016, that lends statewide in Connecticut, including Hartford and New Haven. Its Connecticut page features a $435,500 Connecticut hard money loan it funded for a fix-and-flip in Stamford.
Speed: Easy Street promises term sheets within a day and skips the appraisal on most loans, which lets it advertise 48-hour closings for files that are fully ready.
Connecticut presence: Easy Street lends throughout Connecticut but operates from Texas.
Real estate experience: Easy Street says it works with investors regardless of their experience level or strategy.
Direct lender: Easy Street lends its own capital and makes decisions in-house.
Requirements: Fix-and-flip loans up to 93% LTC and 75% loan-to-value, new construction loans up to 90% LTC, and credit scores as low as 600.
10. New Silver
Founded in 2018, New Silver is a technology-focused direct lender offering fix-and-flip loans, ground-up construction loans, and DSCR loans in Connecticut and seven other Northeast states.
Speed: New Silver's automated underwriting produces a preliminary term sheet and proof-of-funds letter in under five minutes. It has closed rush loans in under five business days, though closings can take 10 business days or longer depending on the area.
Connecticut presence: New Silver lends in Connecticut as part of a multistate footprint.
Real estate experience: Approval runs through automated underwriting, and less experienced borrowers face higher credit minimums.
Direct lender: New Silver is a licensed direct lender, though it also works with outside capital partners.
Requirements: Up to 90% LTC, 75% ARV, and 100% of renovation costs, with loans from $100,000 to $5 million and a 650 minimum credit score (higher for newer investors).