Airbnb lenders specialize in financing short-term rental properties. Unlike most mortgage lenders, they know how to estimate vacation rental income, including seasonal swings in occupancy and nightly rates, and they understand the local regulations that determine whether a property can operate as an Airbnb.
That makes them more likely to approve an Airbnb loan than a lender that doesn’t understand Airbnb properties.
That said, not every Airbnb lender is built the same, so your choice still matters. Many take 30+ days to close, which makes it nearly impossible to compete with fast cash buyers. Others evaluate your personal finances, like your income and DTI, instead of the property itself, and may disqualify you even when the property would earn enough to cover the loan.
So we wrote this guide to help short-term rental investors choose the right lender. We’ll walk through what to look for in a lender so you can qualify and close quickly without drama, then show you how the top Airbnb lenders stack up.
Note: We’re Constitution Lending, a direct lender that has funded hundreds of millions of dollars in DSCR loans for short-term and long-term rentals, closing most within 7 to 14 days. Enter your deal into our pricer to see the rates, terms, and loan amounts you qualify for.
Factors to Consider When Choosing an Airbnb Lender
1. Do they evaluate the property or your personal finances?
Banks that issue a traditional mortgage, and even some private lenders, approve an Airbnb mortgage based on your personal finances. They want high income, long employment histories, low debt-to-income ratios, and more. That can make it difficult to qualify if you’re self-employed, already carry several mortgages, or write off a large share of your income.
We’ve heard from borrowers who bought below market value in a strong cash-flowing area, put down a large down payment, and had a deal that made sense from every angle, only to be turned down because their employment history didn’t fit the lender’s checklist.
Instead, we recommend choosing a lender that approves your mortgage loan based on the property’s finances, namely whether its projected rental income can cover the loan, rather than your personal income and employment.
Read more: 10 Best DSCR Lenders: Considering Speed and Flexibility
2. How fast can they close?
Almost every lender promises a fast closing, but few can actually deliver. It’s common for lenders to say they’ll close in under two weeks, but then take months.
These delays usually stem from the lender’s slow internal processes. It often takes days for a loan officer to even review your file, then they request documents one at a time instead of all at once, creating unnecessary back-and-forth. And underwriters may not ask for your AirDNA report or booking history until late in the process.
So rather than taking a lender at its word, validate its closing speed by checking how quickly it issues quotes, term sheets, and pre-approval letters. These are some of the simplest documents a lender can produce, so if you’re waiting days, the rest of the process will likely drag too.
Look for Airbnb lenders with automated tools that generate all three documents within minutes. It’s a strong sign they’ve built their entire operation around speed, and that usually carries through to underwriting and closing.
3. Do they have real estate investing experience?
This might seem like an unusual question, but it can make the difference between getting your Airbnb deal approved and not.
Many lenders staff their teams with loan officers who have zero real estate investing experience. They enter your deal into an underwriting system and pass along whatever answer comes out. There’s little room for human judgment, so your application can be rejected for missing one small requirement, even when the deal is clearly profitable overall.
For example, you might find an investment property in a popular vacation area with strong year-round demand, but if your credit score falls a few points below the lender’s cutoff, an automated system will often decline it.
A lender with real estate investing experience can look at the deal the way you do. They understand what makes a short-term rental succeed, and they’re far more willing to make an exception when the numbers clearly work.
4. Are they a direct lender or a broker?
One of the most common problems Airbnb investors run into is getting rejected right before closing, after being told everything looked good.
In most cases, the culprit is a broker. Brokers don’t fund loans and don’t make the final decision. Instead, they pass your application along to a lender that actually has the capital.
That’s where things tend to go wrong. A broker may tell you that you qualify based on its own preliminary review. However, if the funding lender spots a problem late in underwriting, it can still decline your loan, even after you’ve been reassured for weeks that everything was fine.
This happens even more often with short-term rental loans, since details like projected nightly income and local rental regulations mean there’s more for the broker to miss.
That’s why we recommend partnering with a direct lender. It funds loans with its own capital and makes every decision in-house, so it can review your application and give you a clear yes or no early in the process, while you still have time to adjust your plans.
5 Airbnb Lenders Ranked Against the Factors Above
1. Constitution Lending: DSCR Loans for Airbnb Investors That Close in 7 to 14 Days
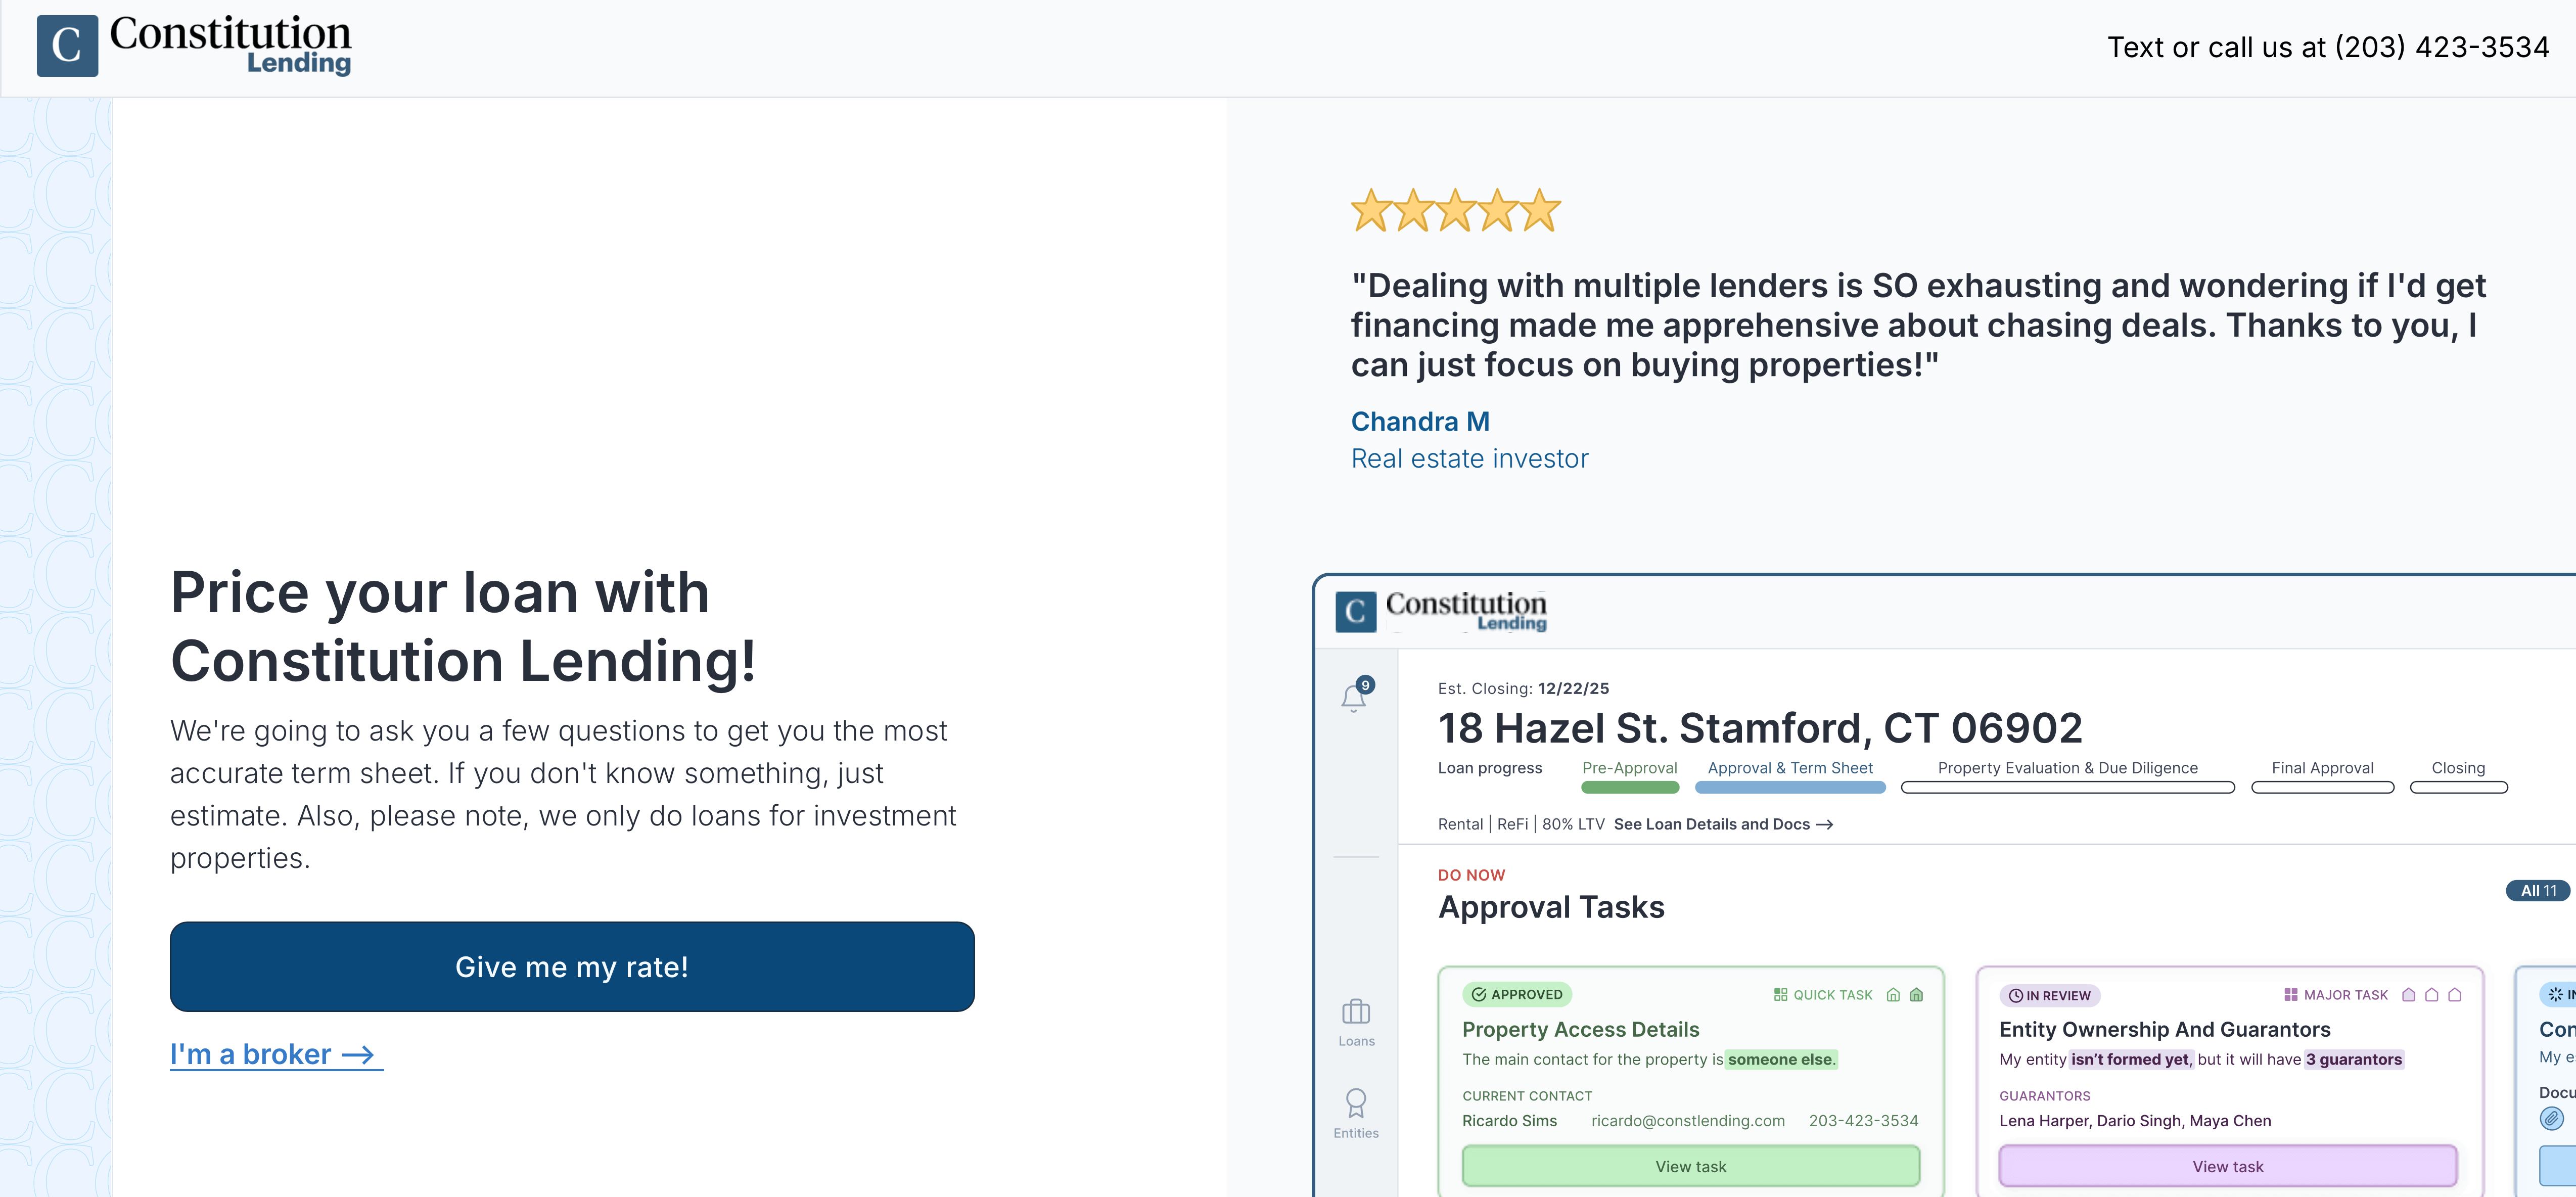
Constitution Lending is a direct lender that provides DSCR loans for Airbnb rental properties and long-term rentals.
Before we started lending, we spent years buying and managing rental properties ourselves, and we ran into the same headaches many Airbnb investors deal with today. Lenders quoted quick closings and then missed them by weeks, and approvals that seemed certain early on fell apart at the last minute.
So we built Constitution Lending to be the lender we couldn’t find as investors: one that moves quickly, evaluates each deal on its merits, and gives borrowers a clear answer early in the process.
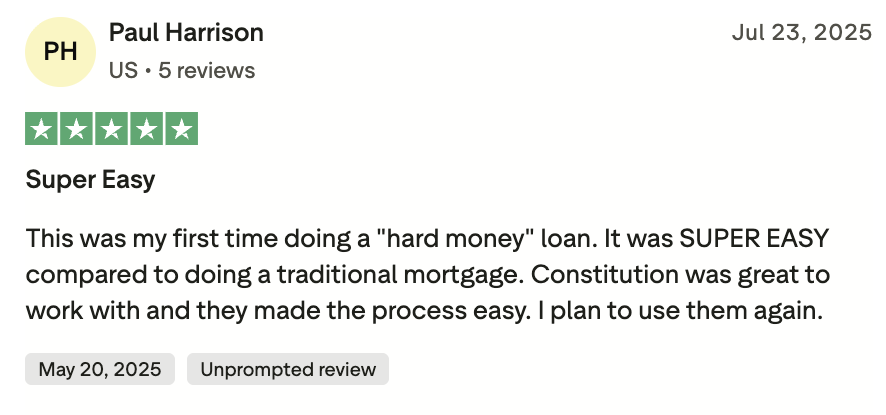
Here’s what borrowers say about working with us:

We Approve Loans Based on What the Property Earns, Not Your Personal Finances
With our DSCR loans, approval centers on the property’s debt service coverage ratio (whether its rental income covers the monthly mortgage payment). We don’t ask for W-2s, pay stubs, tax returns, or an employment history, so being self-employed or already owning several properties won’t count against you.
Read more: DSCR Loan Pros and Cons: A Detailed Guide for Investors
Get a Quote in Minutes and Close in 7 to 14 Days
We built our lending process around automated tools that move your loan from application to the closing table as quickly as possible. Here’s what that looks like:
- Plug the property’s location, type, purchase price, and loan amount into our pricer, along with your credit score, and you’ll see three loan options side by side.
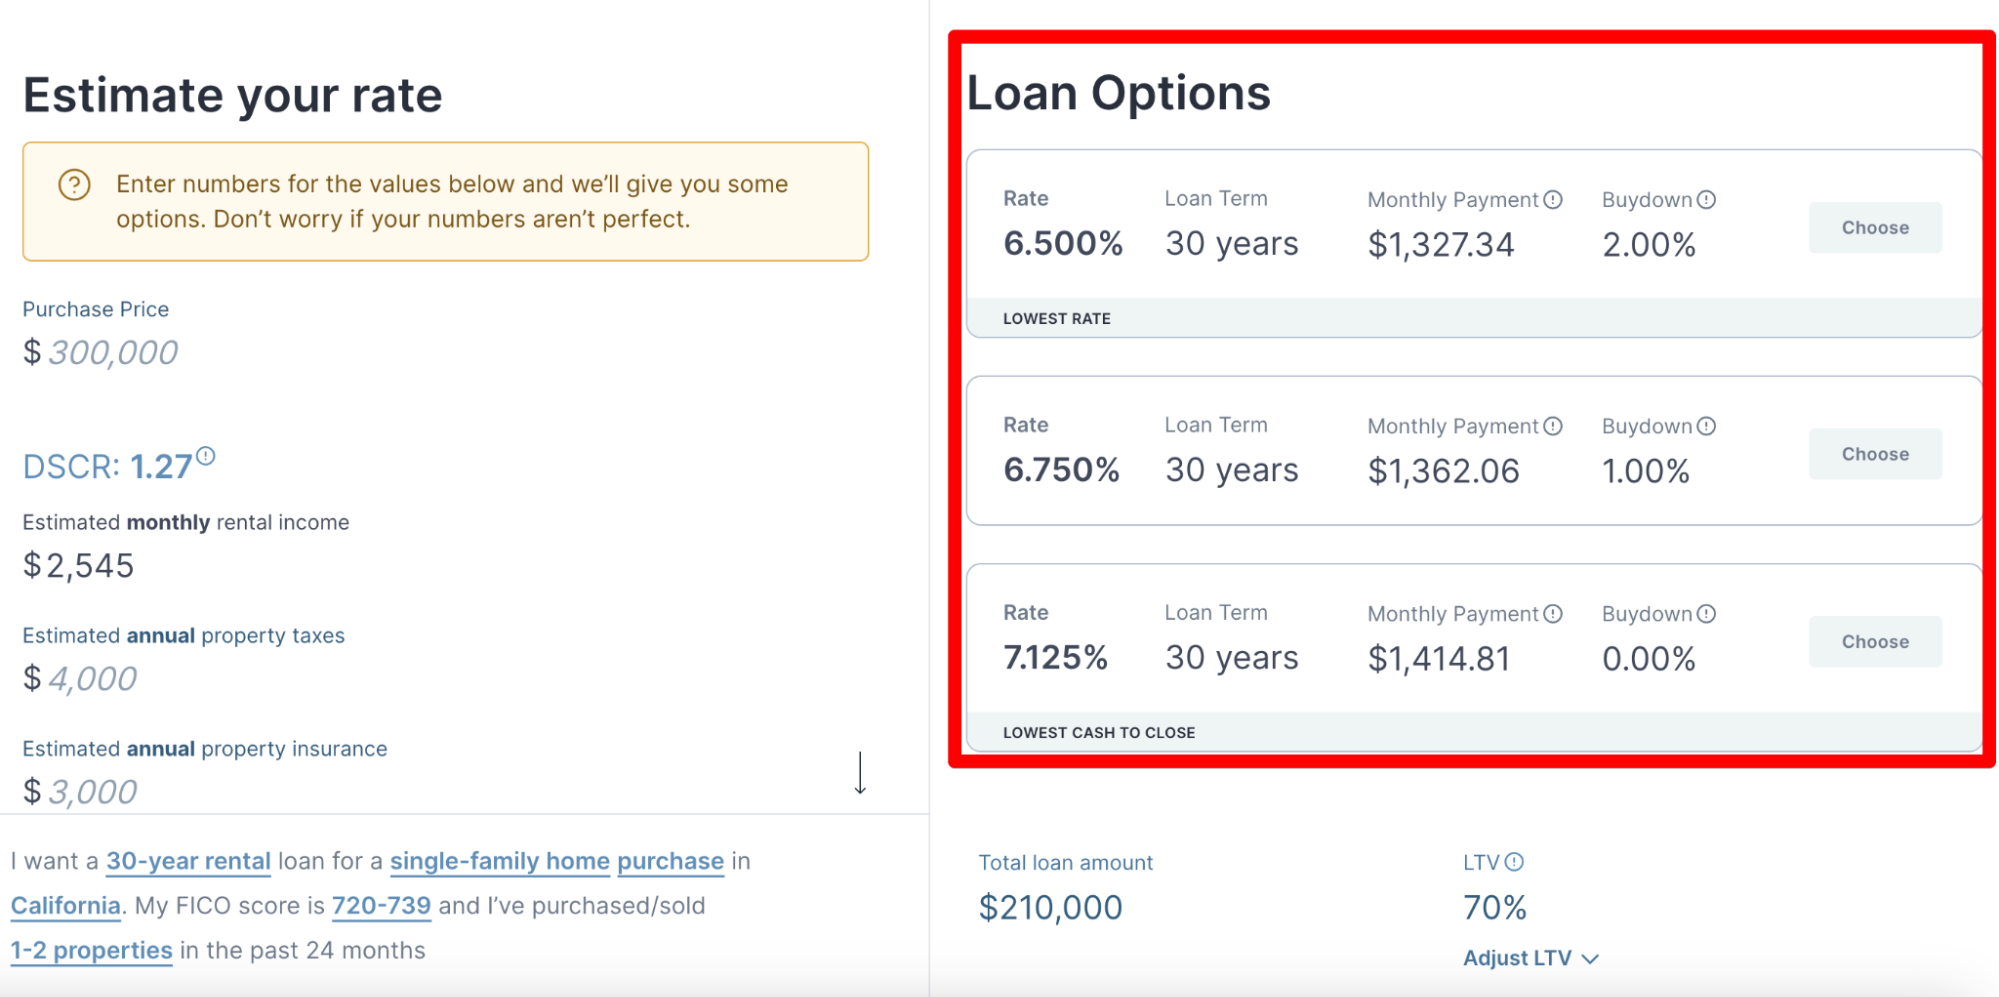
- Pick the option that fits your deal, and your term sheet and pre-approval letter are ready to download on the spot.
- Our documents portal opens at the same time and shows everything we need upfront, so you can upload it all in one sitting and track your loan’s progress from there.
- We close most loans within 7 to 14 days. When borrowers have their paperwork ready from day one, we’ve closed in as few as four days.
Our Team Has Invested in Real Estate, So We Read Deals Like You Would
Because we’ve owned and operated rentals ourselves, we evaluate your Airbnb deal like an experienced investor. We look at what you paid for the property, how much demand the area sees, and what the property can realistically bring in.
That background is what lets us make exceptions. If a property sits in a strong vacation market and the numbers clearly work, a single requirement falling slightly short doesn’t have to end the conversation.
No Brokers or Outside Underwriting
We’re a direct lender, so we fund every loan with our own capital, and our team makes every decision. Once you’ve submitted your documents, we can tell you within hours whether you qualify, so you’re not waiting on a third party that could change its answer days before closing.
Our DSCR Loan Requirements
- Minimum DSCR: 0.75
- Maximum LTV: Up to 80% on purchases and 75% on cash-out refinances
- Minimum credit score: 660
- Loan amounts: $125,000 to $3 million
- Cash reserves: None required
- Income documentation: No income verification and no tax returns
- Eligible properties: Short-term and long-term rentals, including single-family homes, 2- to 4-unit properties, 5- to 20-unit buildings, and condos
- Loan terms: 30-year fixed, with interest-only options available
- Borrowing entity: Individuals or LLCs
Get Started
Have an Airbnb deal in mind? Run it through our automated pricer to see the rates, terms, and loan amounts you’d qualify for in a few minutes.
2. Easy Street Capital

Easy Street Capital is an Austin-based private lender that calls itself the nation’s leader in short-term rental DSCR loans. Its EasyRent program finances long-term, medium-term, and short-term rentals, and its blanket portfolio loans can cover several properties at once.
How it evaluates deals: Easy Street qualifies loans on the property’s projected income divided by its monthly payment, with no DTI requirement. It leans heavily on AirDNA data and says that when it compared its last 25 short-term rental loans against AirDNA’s projections, actual earnings came within 0.4%. Newer STR investors should know that the full AirDNA projection is generally reserved for experienced short-term rental operators, while others may be qualified on long-term market rent from the appraiser.
Speed: According to third-party reviews, Easy Street’s short-term rental loans closing speed is about 30 days.
Direct lender: Easy Street lends its own capital, though it also runs a broker program, so some borrowers reach it through a broker rather than directly.
Requirements: STR loans range from $100,000 to $3 million, with portfolio loans up to $5 million. Easy Street lends nationwide except in Nevada, North Dakota, and South Dakota.
3. Newfi Lending
Newfi Lending is a California-based mortgage lender that offers DSCR loans for investors alongside a full menu of conventional loans, including VA and FHA. That makes it a practical option for investors who want their Airbnb financing and personal home loan with the same company.
How it evaluates deals: Newfi’s DSCR program uses the property’s rental income instead of your personal income, and appraisers can support the calculation with market rents or historical short-term rental income. Newfi also markets its DSCR cash-out refinance to investors looking to replace a high-cost hard money loan on an existing short-term rental.
Requirements: Newfi’s DSCR loans start at a 640 minimum credit score and include a 40-year term option, which lowers the monthly payment on the same loan amount. Its DSCR loan minimum is $150,000, and it finances 1- to 4-unit residential properties only.
4. Rabbu
Rabbu is a short-term rental data and investment platform best known for its Airbnb revenue calculator, which estimates a property’s income using data from comparable listings.
How it evaluates deals: Rabbu’s projections are built for short-term rental investors, and Rabbu says lenders accept them for DSCR underwriting. Its guides also point out that conventional mortgage lenders often turn down profitable Airbnb deals because they don’t count short-term rental income.
Direct lender: Rather than funding loans itself, Rabbu connects investors with a network of DSCR lenders. That makes it a useful starting point for comparing options, but the final approval comes from whichever lender in its network funds your loan.
5. Kram Capital
Kram Capital is an independent lending firm that finances commercial and investment properties, including multifamily and bridge loans. Short-term rentals are one of its main focuses, and the company describes itself as a source of financing for short-term rental, vacation rental, Airbnb, and foreign national properties nationwide.
Short-term rental focus: Kram runs a dedicated Airbnb financing program that’s open to both new and seasoned investors. For investors who own several properties, it also provides blanket financing that can cover portfolios of short-term and long-term rentals under one loan.
Requirements: Kram’s STR loans go up to $3 million and cover single-family homes, condos, duplexes, and townhomes. Its minimum loan amount is $200,000, which puts some lower-priced vacation properties below its range, and its program doesn’t extend to every state.