DSCR loans are approved based on whether a property’s rental income covers its monthly mortgage payment, unlike a traditional mortgage, which evaluates your entire personal financial profile (e.g., income, debt-to-income ratio, employment history, tax returns).
For first-time investors, that structure offers several advantages:
- No income documentation. You don’t need W-2s, tax returns, or pay stubs, which helps if you’re self-employed or write off much of your income.
- Personal debts don’t count against you. Student loans, a car payment, or your own mortgage won’t disqualify you, since DSCR lenders focus on property cash flow rather than your debt-to-income ratio.
- Faster closings. Without income and employment verification, DSCR loans typically close faster than conventional loans, helping you compete with cash buyers.
- You can buy in an LLC from the start. Owning the rental through an LLC can help shield your personal assets if the property faces a lawsuit. A conventional mortgage typically doesn’t allow LLC ownership.
Those benefits aside, not every DSCR lender treats first-time investors the same, so your choice matters. Many DSCR lenders disqualify first-time investors or offer worse terms, such as lower LTVs, larger down payments, extra cash reserves, or a requirement that you already own a home.
Worse, borrowers often don’t learn they’ve been disqualified until weeks after applying, near the closing date. By then, they risk losing their earnest money deposit and have to start over with another lender.
So, in this article, we cover what first-time investors should look for in a DSCR lender, then compare the best DSCR lenders for first-time investors against those factors. If you want to learn the basics first, read our guide covering the pros and cons of DSCR loans.
Use our automated pricer to see the rates and terms you qualify for and compare multiple loan scenarios.
Factors to Consider Before Choosing a DSCR Lender as a First-Time Investor
1. Do they offer first-time investors less favorable terms?
Many DSCR lenders set extra requirements and stricter terms for first-time investors. So, before applying, check the lender’s guidelines or ask a loan officer whether any of the following apply to you:
- Cash reserves. Some lenders ask first-time investors to show several months of mortgage payments in savings on top of the down payment.
- Higher minimum DSCR. Some lenders require a higher minimum debt service coverage ratio, sometimes 1.0 to 1.2 or more.
- Lower loan-to-value limits. A lower LTV means a larger down payment, which is often the hardest hurdle for a new investor.
- Higher interest rates. Some lenders charge first-time investors a higher rate, even when the deal itself is strong.
We advise choosing a DSCR lender that prices your loan based on the property’s cash flow alone and doesn’t add extra requirements just because you’re a first-time investor.
2. Does the lender have real estate investing experience?
Few borrowers think to ask whether their lender has real estate investing experience, but it matters.
Loan officers with no real estate investing experience struggle to spot a deal’s profit potential the way an investor would. Instead, they enter your numbers into an underwriting algorithm that approves or declines your loan based on rigid requirements. There’s no room for human judgement.
As a result, lenders may still reject a strong deal over a technicality. For example, you might buy a property below market value in a neighborhood where rents are climbing, but if the appraiser’s rent schedule shows the current tenant’s lease is below market rent, or the property’s DSCR lands just under the minimum, you can still get rejected.
We recommend working with a DSCR lender whose team has bought and managed rental properties. They look at the deal the way an investor would, and are more likely to make exceptions when the numbers make sense.
3. Do they use automated tools to speed up closing?
DSCR lenders often promise funding within one to two weeks, but fail to deliver because they still process applications manually. Your file may wait days for a loan officer to review it, document requests arrive in stages rather than all at once, and several people may need to sign off on your loan.
So, instead of taking a lender’s word on closing speed, check how quickly it can provide a quote, term sheet, and pre-approval letter. These are the fastest documents a lender can produce, so if it takes days to send them, expect underwriting, the appraisal, and closing to move slowly too.
We recommend choosing a lender with an online pricer that issues all three documents instantly and a portal for uploading your paperwork in one place. Both signal a lender built for speed.
4. Are they a direct lender or a broker?
We don’t advise working with mortgage brokers, since they’re one of the main reasons last-minute rejections and complications are so common in private lending.
That’s because they don’t fund your loan; they submit your file to an actual lender that makes the final decision.
A broker may believe you can qualify, but if the actual lender spots a problem the broker overlooked, your loan can be declined even after the broker told you that you qualified. We’ve spoken to borrowers who had their loans rejected the day before closing and lost their deposits.
A direct lender funds loans with its own capital and makes its decisions in-house, so the approval you receive early in the process comes from the same team that will fund your loan. That means you’ll know early on whether your loan will close.
10 DSCR Lenders Compared to the Factors Above
1. Constitution Lending: DSCR Loans for First-Time Investors with No Minimum DSCR
Constitution Lending is a direct lender that provides DSCR loans to real estate investors of every experience level, including those buying their first rental property.
Before starting Constitution Lending, we built our own portfolio of rental properties and dealt with many of the lenders investors still use today. Their advertised timelines rarely held up, and lenders would tell us we qualified, only to decline the loan weeks later as closing approached.
We started Constitution Lending so that investors, including first-timers, could close quickly and know early in the process whether their loan would be approved.
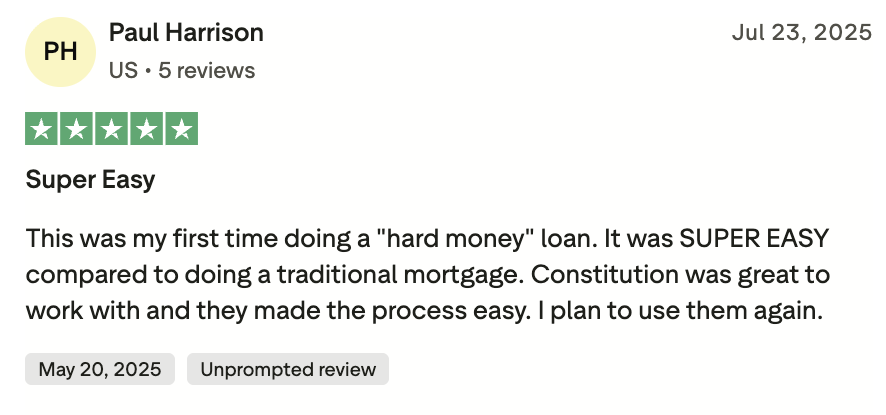
Here’s what borrowers say about working with us:

Below, we cover how we deliver on each of the factors above.
We Offer First-Time Investors the Same Terms as Experienced Ones
Your experience level doesn’t affect the rate or LTV we offer. We base your terms on the rental itself, including the purchase price, the rent it generates, and its DSCR, so a first-time investor with a strong property receives the same pricing and leverage as someone who owns ten rentals.
You can confirm this using our pricer. Run your deal once as a first-time investor, then enter the same numbers as someone with several properties. Your rate and LTV will stay the same because our pricing doesn’t depend on your track record.
We Review Your Deal as Investors, Not Through an Algorithm
Because our team has bought and managed rental properties, the people evaluating your loan understand what it’s like to buy your first one.
That allows us to look at your deal the way you do: what you’re paying for the property, what it rents for today, what it could realistically rent for, and how the surrounding market is trending.
With that perspective, we can make exceptions for deals other lenders reject. For example, if you buy a rental below market value or in a neighborhood where rents are rising, you may still qualify even if the property falls short on one of our requirements.
Our Automated Pricer and Documents Portal Help Us Close in 7 to 14 Days
As we covered above, the speed at which a lender issues quotes, term sheets, and pre-approval letters is a good indicator of how quickly it will close.
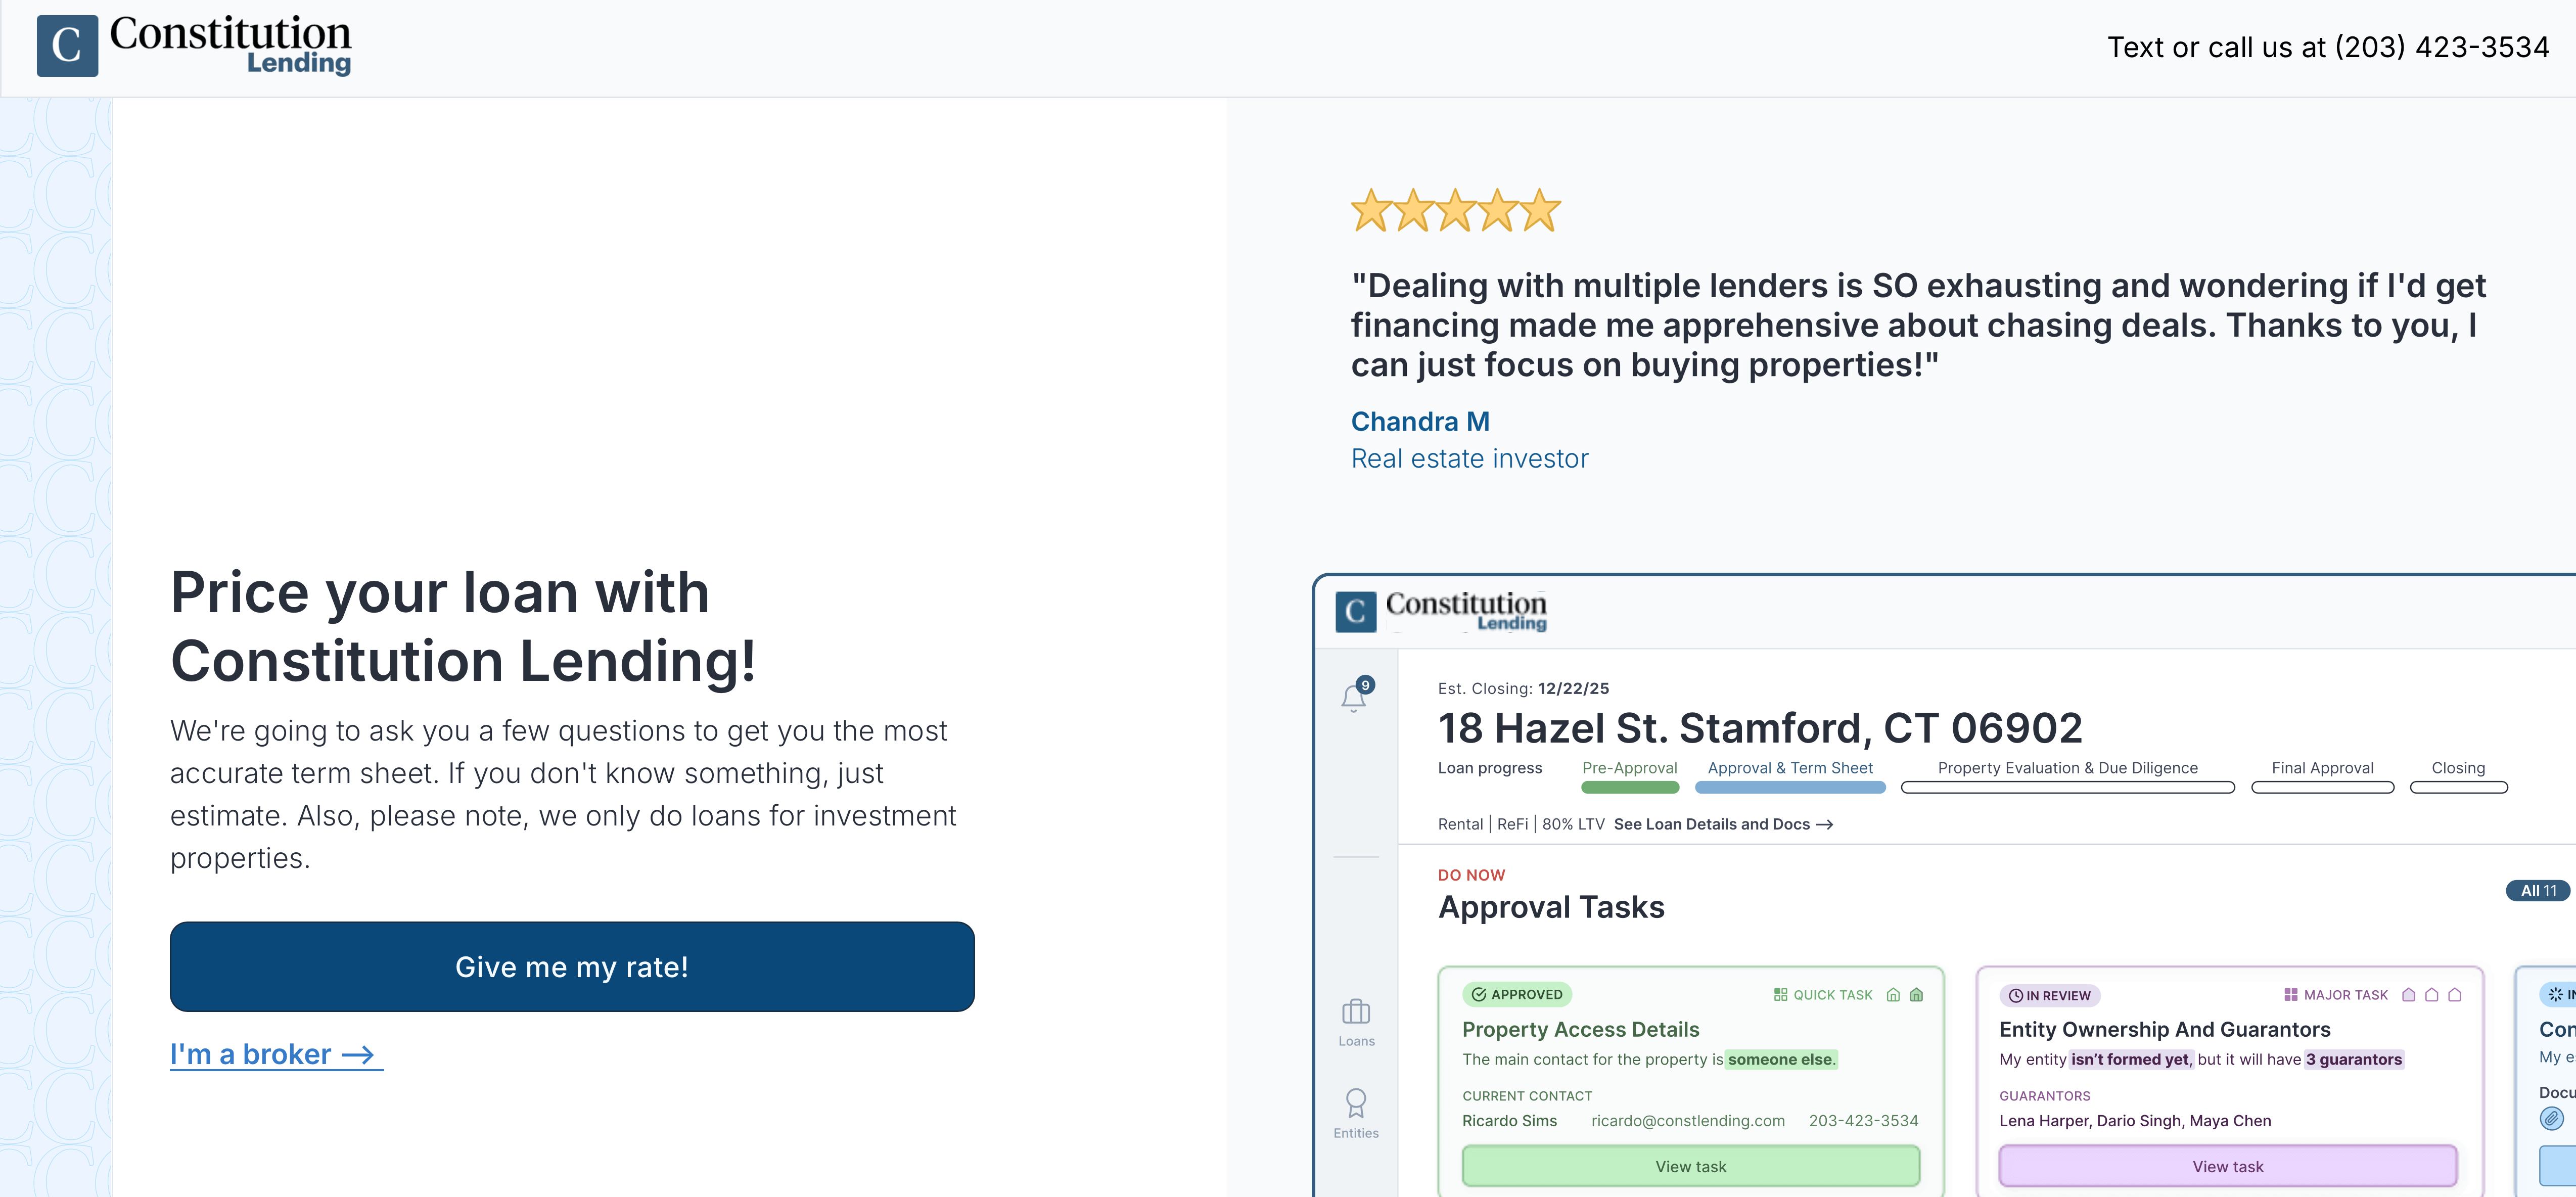
Our automated pricer produces all three immediately, so you can begin submitting documents without waiting for a loan officer to contact you.
Here’s how the process works:
- Enter a few details about the rental into our pricer, such as its location, property type, purchase price, loan amount, and your credit score. The pricer returns three loan options, each with its interest rate, monthly payment, and buydown options.
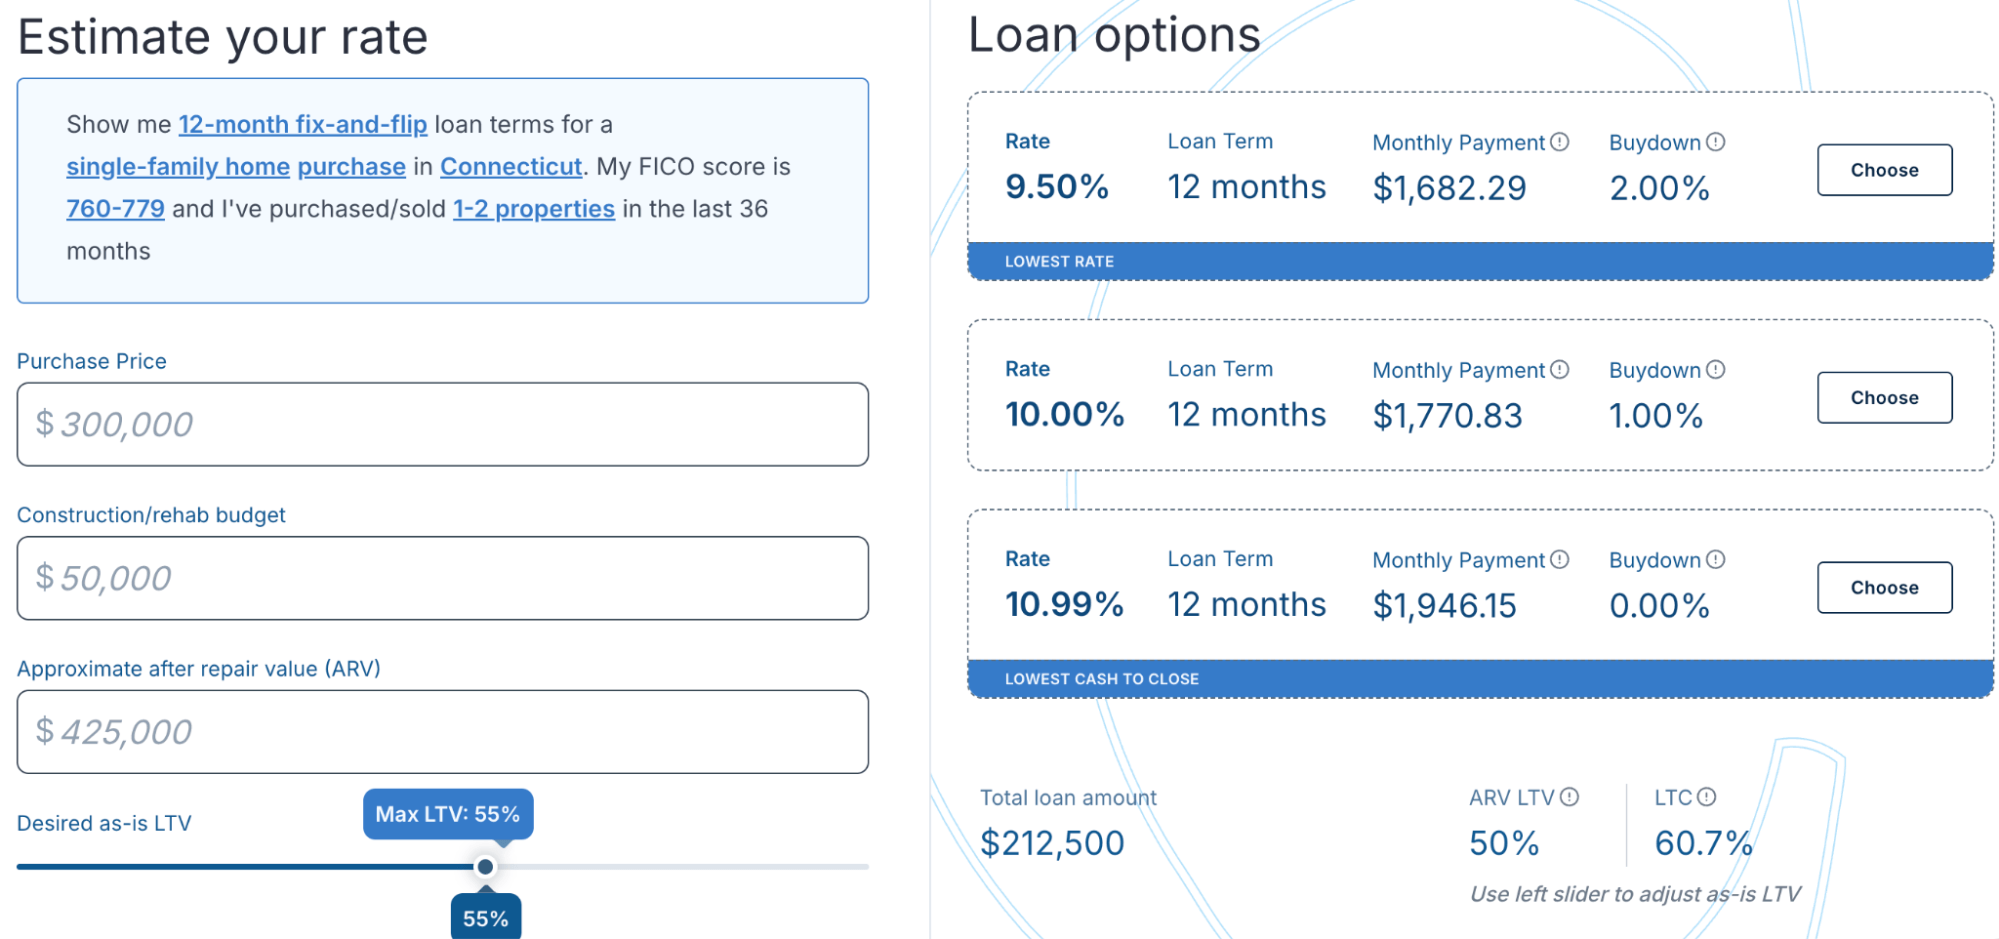
- Adjust the purchase price, LTV, and other inputs to see how each change affects your rate, DSCR, and monthly payment.
- Select the quote you prefer and enter your name and email. You’ll receive a term sheet, a pre-approval letter, and access to our documents portal right away.
- Upload your required documents, such as bank statements, entity documents, the purchase agreement, and lease information, through the portal.

- Track your application’s progress in the portal and message our team with any questions.
- Once we’ve reviewed your documents, we schedule your closing with the title company.
Most of our DSCR loans close within 7 to 14 days. When borrowers have their documents ready from the start, we’ve closed in as little as four days.
We Fund Every Loan with Our Own Capital
As a direct lender, we fund your loan ourselves and make the final decision, rather than passing your file to another lender.
Since we set our own lending criteria, we can tell you whether you qualify within hours of reviewing your documents. You’ll know where you stand early in the process, without a third party’s underwriting team stepping in near your closing date.
Our DSCR Loan Requirements
Our requirements center on the property rather than your income or investing history:
- Minimum DSCR: None
- Maximum LTV: Up to 80% on purchases and 75% on cash-out refinance loans
- Minimum credit score: 660
- Loan amounts: $125,000 to $3 million
- Cash reserves: None required
- Homeownership or mortgage history: Not required
- Income verification: No tax returns, W-2s, or pay stubs
- Eligible properties: Single-family rentals, 2- to 4-unit properties, 5- to 20-unit buildings, and condos
- Loan terms: 30-year fixed, with interest-only payments available
- Prepayment penalties: Flexible step-down options
- Borrowing entity: Individuals or LLCs
- Short-term rentals: Eligible
Get Started
Constitution Lending has helped hundreds of first-time investors finance rental properties and compete with cash buyers for undervalued properties. Use our automated pricer to compare loan scenarios and receive instant quotes.
2. Griffin Funding

Griffin Funding is a direct-to-consumer mortgage lender that has closed more than 2,100 DSCR loans totaling over $650 million. It holds state mortgage licenses in 47 states plus Washington, D.C., which is uncommon among DSCR lenders.
First-time investors: Griffin has no minimum DSCR and offers a no-ratio program, along with a 620 minimum credit score, which keeps its loans within reach for newer investors and properties with thin margins.
Speed: Applications run through LIA, Griffin’s proprietary AI underwriting platform. Its fastest DSCR closing took 6 days, though its average is 34.
Direct lender: Griffin underwrites and funds its loans in-house.
Requirements: Loans go up to $4.5 million, borrowers with 740+ credit can put down as little as 15%, and you can borrow through an LLC.
3. Kiavi

Kiavi is one of the largest non-bank lenders to residential investors, and Figure Technology Solutions completed its acquisition of the company on September 1, 2026. Its DSCR loans are now originated and funded by Figure Lending LLC under the Kiavi brand.
First-time investors: Kiavi’s single-property DSCR loans don’t require investing experience, but its portfolio loans do, so beginners are limited to financing one rental at a time.
Speed: You can check your rate online without a hard credit pull. Third-party reviews put DSCR closings at around 20 to 30 days.
Direct lender: Kiavi lends directly through its online platform. With the Figure integration underway, confirm your terms in writing before going under contract.
Requirements: DSCR as low as 0.8 for eligible scenarios, up to 80% LTV, and loans from $100,000 to $3 million, with 30-year fixed, adjustable-rate, and interest-only payment options.
4. Lima One Capital

Lima One Capital has financed investors from Greenville, South Carolina, since 2010 and is backed by MFA Financial, a publicly traded REIT. Alongside DSCR loans, it offers bridge loans, fix-and-flip loans, and construction financing.
First-time investors: Lima One’s minimum DSCR is 1.0, adjusted based on borrower experience and property type, so first-timers may face a stricter cutoff than seasoned investors.
Speed: Underwriting, appraisal management, and servicing all stay in-house, and its rental loans close in about 21 days on average.
Direct lender: Lima One funds its own loans.
Requirements: Loans from $100,000 to $2.5 million, up to 80% LTV on purchases and 75% on cash-out refinances. Investors refinancing a renovated property through its Fix2Rent program can skip the usual seasoning requirements.
5. Deephaven Mortgage
Deephaven Mortgage is a non-QM lender that describes its DSCR underwriting as flexible and pro-borrower, and it distributes its loans through correspondent lenders and mortgage brokers.
First-time investors: Deephaven accepts first-time investors but caps them at 70% LTV, compared with up to 80% for experienced borrowers. Its correspondent product matrix has also listed first-time homebuyers as ineligible.
Direct lender: Because Deephaven works through correspondents and brokers, most borrowers reach it through a third party rather than directly.
Requirements: Up to 80% LTV for experienced investors, with first-time investors limited to 70%.
6. Supreme Lending
Supreme Lending is a retail mortgage lender that operates through local branches across the country and offers a DSCR program alongside traditional mortgage products.
First-time investors: Supreme’s DSCR program accepts first-time investors, but limits them to 75% LTV. Borrowers who have never owned a home don’t qualify, which rules out many renters buying their first property.
Requirements: Both first-time and experienced investors are eligible, and foreign nationals can qualify. First-time investors are capped at 75% LTV, which typically means a 25% down payment.
7. Visio Lending

Founded in Austin, Texas, in 2012, Visio Lending focuses exclusively on rental property loans and was named the No. 1 DSCR lender in the country by Scotsman Guide based on 2024 volume. It has originated more than $4.2 billion in loans.
First-time investors: Visio’s standard DSCR floor is 1.0, with ratios below that reviewed case by case, so a first rental with tight margins may not fit its standard program.
Speed: Visio orders the appraisal when you apply and aims to close within 30 days.
Direct lender: Visio funds its own loans, though much of its volume comes through a network of more than 1,000 mortgage brokers. Applying directly puts you in touch with the decision-maker.
Requirements: Loans start at $75,000, with up to 80% LTV on purchases and 75% on cash-out refinances.
8. Angel Oak Mortgage Solutions
Atlanta-based Angel Oak Mortgage Solutions has originated more than $19 billion in non-QM loans since its founding in 2013. Its Investor Cash Flow loan is its DSCR program for rental property investors.
First-time investors: Angel Oak’s standard minimum DSCR is 1.0, though it offers a no-ratio option for borrowers with a 700+ credit score at 75% LTV or lower.
Speed: A rental automated valuation model sets the property’s DSCR at the start of the process and locks it for the loan, which reduces late surprises.
Direct lender: Angel Oak is a wholesale and correspondent lender, so most investors reach it through a mortgage broker rather than directly.
Requirements: Loans from $100,000 to $3 million, with up to 85% LTV for borrowers with 720+ credit and 75% LTV at 680.
9. Easy Street Capital

Easy Street Capital is an Austin-based private lender founded in 2016, best known for its hard money loans. Its EasyRent program covers long-term and short-term rentals and has funded more than $3 billion in DSCR loans over the past four years.
First-time investors: EasyRent has no minimum DSCR, and Easy Street says it works with investors regardless of experience. Weaker ratios receive lower leverage or higher pricing rather than an outright decline.
Speed: Easy Street’s DSCR page says rental loans close in as little as 30 days.
Direct lender: Easy Street lends its own capital and makes decisions in-house.
Requirements: Loans from $100,000 to $3.5 million, with up to 80% LTV on purchases and 75% on cash-out refinances.
10. New Silver
Founded in 2018, New Silver is a technology-focused direct lender with DSCR loans offered alongside its hard money and bridge loans.
First-time investors: New Silver doesn’t require prior investing experience for its DSCR loans and accepts ratios as low as 0.75.
Speed: Term sheets are issued instantly online, and DSCR loans typically close in 2 to 4 weeks.
Direct lender: New Silver funds its own loans.
Requirements: A 660 minimum credit score, up to 80% LTV, and loans from $150,000 to $3 million on 1- to 8-unit residential properties, including short-term rentals.