We recommend considering four factors before choosing a fix-and-flip lender, since they separate lenders who close quickly from those who cause avoidable delays and complications:
- How quickly do they issue quotes, term sheets, and pre-approval letters? Most hard money lenders overpromise in their advertising, saying they close within days but then take months. Instead of taking a lender at their word, test their closing speed by how fast they send these documents. If that takes multiple days, expect the rest of the process to drag as well.
- Are they a direct lender or a broker? Brokers are a common cause of last-minute rejections because they don't fund your loan and therefore aren't the decision-maker. As we discuss in more detail below, this can lead to last-minute rejections and drama. Choose a direct lender, since they can give you a definitive yes or no early in the process.
- How do they handle rehab draws? It’s normal for fix-and-flip lenders to release your renovation funds in draws as work is completed. But lenders that require in-person inspections for each draw can cause delays. Go with a lender that accepts virtual inspections, since they typically release funds faster.
- Do they offer financing options post-renovation? If you keep the property as a rental, you'll need to refinance into long-term financing such as a 30-year DSCR loan. A new lender has to restart underwriting from scratch, which keeps you on higher-rate, short-term financing for longer. A lender that offers both already has your file and can refinance you faster.
Below, we compare the top fix-and-flip lenders for fast closings against these four factors.
We start with our own fix-and-flip process at Constitution Lending and walk through how we deliver on each factor. Then we cover other lenders you're likely to come across in your research.
Note: Constitution Lending is our own company, so we've done our best to write an objective comparison. That said, we've funded hundreds of millions of dollars in loans for flippers and typically close in 7 to 14 days. To see what you qualify for, enter a few deal details into our automated pricer for an instant quote, term sheet, and pre-approval letter.
1. Constitution Lending: Fix-and-Flip Loans That Close in 7 to 14 Days

Before we started lending, we spent years flipping properties ourselves, so most of the problems covered in this article are ones we experienced firsthand.
Our lenders would promise a one-week closing and then take several weeks to fund. In that time, cash buyers would beat us to undervalued properties we found first.
The delays didn't end at closing. Most of our lenders took days to inspect completed work and release the next draw, so our projects frequently got delayed.
We founded Constitution Lending to fill that gap in fix-and-flip financing. We built our process to help borrowers compete with cash buyers and to keep renovation funds moving once the project starts.
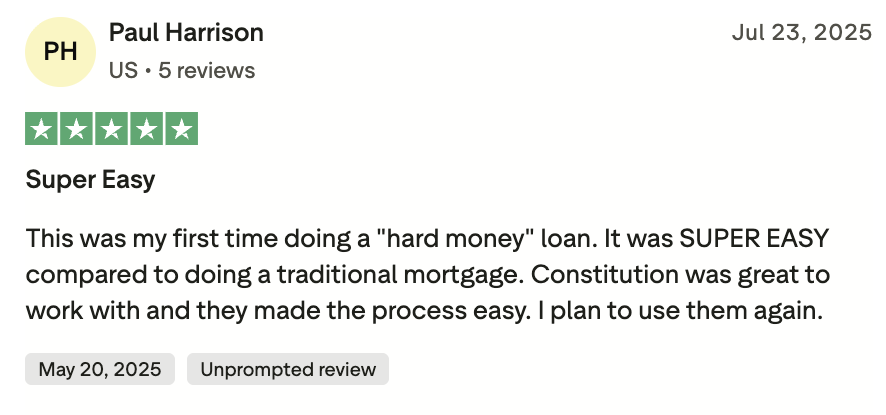
Here's what borrowers say about working with us:


We Issue Instant Quotes and Term Sheets and Close in 7 to 14 Days
Most fix-and-flip lenders advertise closings within a week or two, but in practice many take a month or longer. That's because they still run loans through the same slow, bureaucratic internal processes as big banks and credit unions.
When we were flipping, we learned to judge a lender's closing speed by how quickly they sent us a quote, term sheet, and pre-approval letter. Those documents take the least work, so a lender that needs days to send them rarely speeds up as closing approaches.
We built our process around automated tools and systems so you can move from application to closing in 7 to 14 days. Here's how it works:
- Get your quote, term sheet, and pre-approval letter instantly by entering a few details about the property into our automated pricer.
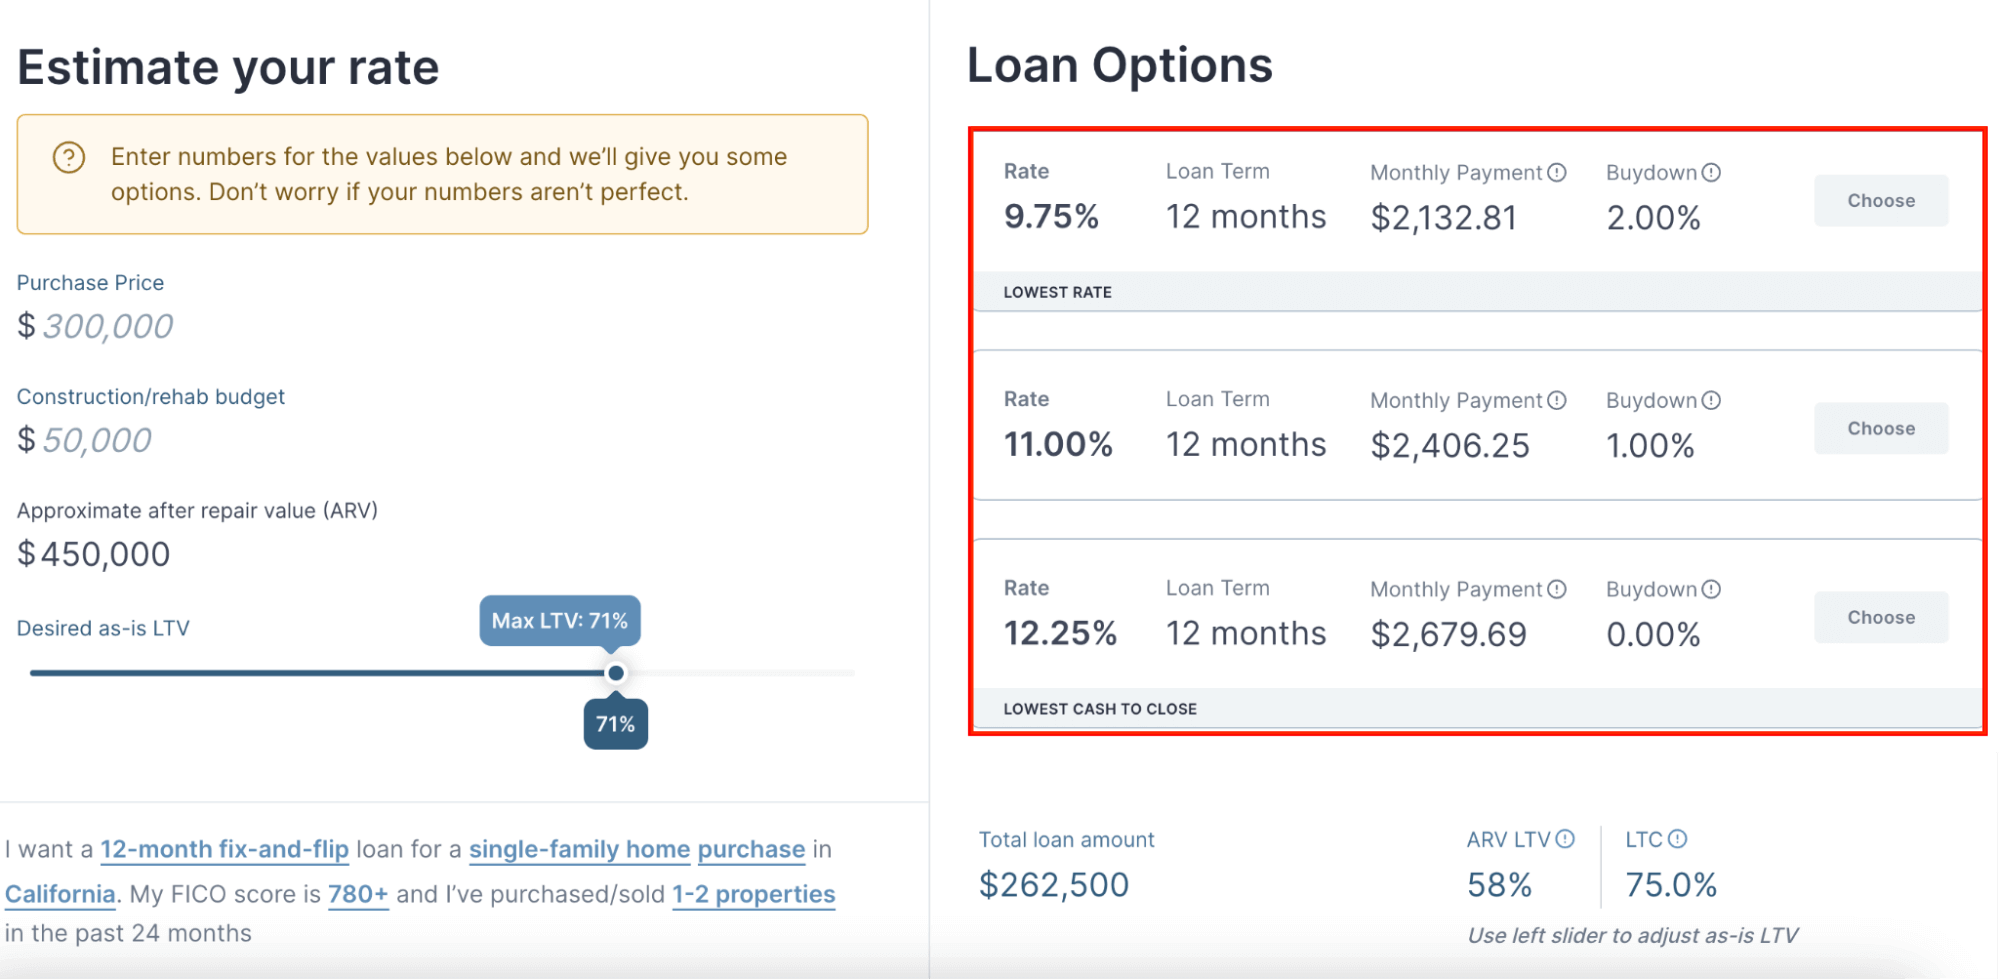
- Submit all your documents in one place. You get access to our documents portal at the same time. It lists every document your loan requires, including bank statements, entity documents, proof of insurance, and your renovation budget so that you can upload everything in one go.
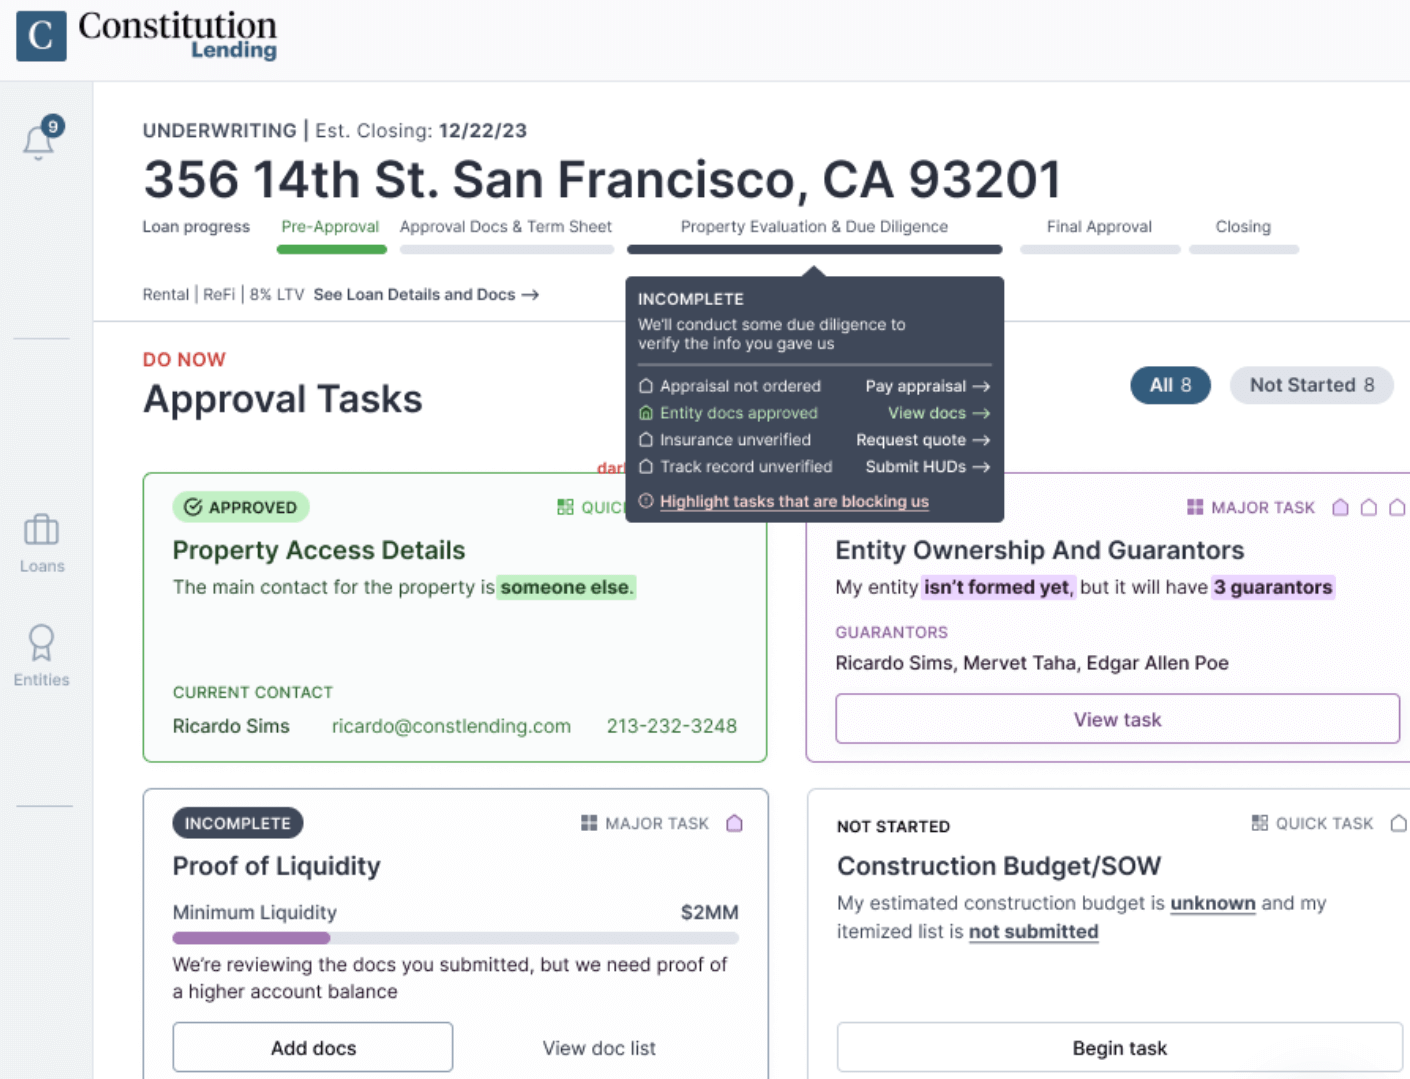
- Close in 7 to 14 days. Once we receive your documents, we underwrite your loan and close within 7 to 14 days. When borrowers need to close urgently, we've funded it in as little as 4 days.
- Get your draws funded the same day. As work is completed, submit photos and videos through the portal, and we release your funds the same day.
We Lend Our Own Capital, So You Know Within Hours Whether Your Loan Will Close
Many companies that market themselves as private money lenders are actually brokers. They don't fund loans, but act as middlemen, passing your file to an actual lender.
That setup is why late rejections are so common. A broker may give you an early approval based on their initial read. But if the actual lender finds problems during their underwriting process, you could get rejected weeks into the process after being told you qualify. When we were flipping, we had loans rejected the day before closing.
At Constitution Lending, we're a direct lender, which means we lend our own money and make every decision in-house. Because we set our own underwriting requirements, we can tell whether you qualify as soon as we review your file, and you'll typically have a clear yes or no answer within hours of submitting your documents.
If we spot a problem, we tell you right away so you can fix it and resubmit, rather than finding out after your earnest money is at risk. You get your answer early in the process, without any last-minute surprises.
We Accept Virtual Draw Inspections and Release Funds the Same Day
One of the most common causes of renovation delays is a lender that requires an in-person inspection before every draw. After you submit a draw request, the lender has to schedule a third-party inspector, wait for them to visit the property, and then review their report before releasing any funds.
While you wait, your contractors may pause work until they're paid, and your interest and carrying costs keep adding up.
At Constitution Lending, we accept virtual inspections. When a stage in your scope of work is complete, upload the photos and video through our portal. A loan officer reviews your submission and releases your next round of funds, typically the same day you submit it.
Refinance Into a 30-Year DSCR Loan Without Switching Lenders
If you decide to keep the property as a rental after the renovation, you'll need to refinance your hard money loan into long-term financing.
With most lenders, that means applying somewhere new and repeating the whole process: a new application, a round of document requests, appraisals, and underwriting reviews. That can take weeks, and you keep paying the higher interest rates of your hard money loan the entire time.
At Constitution Lending, we offer 30-year fixed-rate DSCR loans that you can use to refinance your fix-and-flip loan.
Because we've already underwritten your property and collected your documents, you don't have to start the process over. We also have a record of the completed work from your draw photos and videos, which gives our team a clear picture of the finished property before the refinance begins.
Read more: 5 Best DSCR Lenders & How to Choose
Secure Fast Fix-and-Flip Loans at Competitive Rates with Constitution Lending
Generate instant quotes for your fix-and-flip loan by plugging a few details about your deal into our automated pricer.
2. Lima One Capital

Lima One Capital is a private real estate lender based out of South Carolina. Its FixNFlip program finances 1- to 4-unit distressed properties with up to 95% loan-to-cost, 75% loan-to-value, and up to 100% of the rehab budget.
What we like about Lima One is that they handle underwriting, appraisals, construction management, and draw processing in-house rather than through outside vendors. That reduces handoffs between companies and speeds up funding.
Investors who decide to hold a property can move into a long-term rental loan through Lima One's Fix2Rent program. The refinance waives seasoning requirements and uses the original FixNFlip appraisal to set the after-repair value.
However, funding speed is the main tradeoff. Published comparisons report that Lima One funds FixNFlip loans within three weeks for repeat borrowers, which can be too long to hold a seller who has cash offers on the table.
3. RCN Capital

RCN Capital is a nationwide private direct lender for real estate investors. The company has originated more than $8.2 billion across over 37,000 loans, and its products include fix-and-flip and bridge loans, DSCR rental loans, and ground-up construction financing.
RCN's fix-and-flip program can fund up to 100% of the purchase price and 100% of renovation costs for its most qualified borrowers, capped at 75% of ARV. Terms run 12 to 18 months, and interest is charged only on the outstanding balance rather than on undrawn rehab funds.
The company also moves quickly at the front end of the process. RCN says it issues term sheets the next business day for most short-term loans and makes pre-approval decisions within 24 hours of a complete submission.
Investors who want to keep a finished property as a rental can refinance into RCN's 30-year long-term rental program. Having both products with the same lender means the refinance doesn't require a new application somewhere else.
The minimum credit score for RCN's fix-and-flip loans is generally 650. Leverage is tiered by experience, and the highest levels are reserved for investors with 10 or more completed flips and a 720+ credit score.
4. Easy Street Capital

Headquartered in Austin, Texas, Easy Street Capital is a private direct lender founded in 2016 by Stephen Hagerman. The company originated roughly $1.2 billion in loans in 2024 and focuses on fix-and-flip, DSCR rental, and new construction loans.
Fast funding is the core of Easy Street's pitch. Its EasyFix program issues term sheets within 24 hours, requires no appraisal on most loans, and advertises closings in as little as 48 hours when every party is ready.
Its draw process avoids site visits as well. Borrowers submit draw requests with invoices or receipts, and Easy Street sends a link to its inspection phone app so the completed work can be verified remotely.
Easy Street's EasyRent DSCR program gives investors a path into long-term financing once a renovation is finished. The company reports funding more than $3 billion in DSCR loans over the past four years.
EasyFix accepts credit scores as low as 600 and finances up to 90% of total project costs. Easy Street lends in most states but excludes Minnesota, Nevada, North Dakota, and South Dakota, along with the Baltimore, Chicago, and Detroit metro areas.
5. LendingOne
LendingOne is a direct private lender that has since funded more than $11 billion across over 16,000 investment property loans.
Its fix-and-flip loans cover up to 92.5% LTC and 100% of the rehab budget, with 12-month terms, interest-only payments, and loan amounts up to $3 million. LendingOne doesn't charge prepayment penalties or interest on undrawn rehab funds, which benefits investors who sell ahead of schedule.
LendingOne runs its draw process virtually, so borrowers can submit draw requests straight from their phones. The company says same-day draws are available through this process.
Its Fix to Rent program lets investors move from a fix-and-flip loan into a DSCR rental loan once the renovation is complete. Investors whose exit strategy is to rent the property can handle both stages with one lender.
LendingOne also doesn't require W-2s or tax returns on its rehab loans. Its pricing is weighted toward experience, so newer investors typically receive less favorable terms.